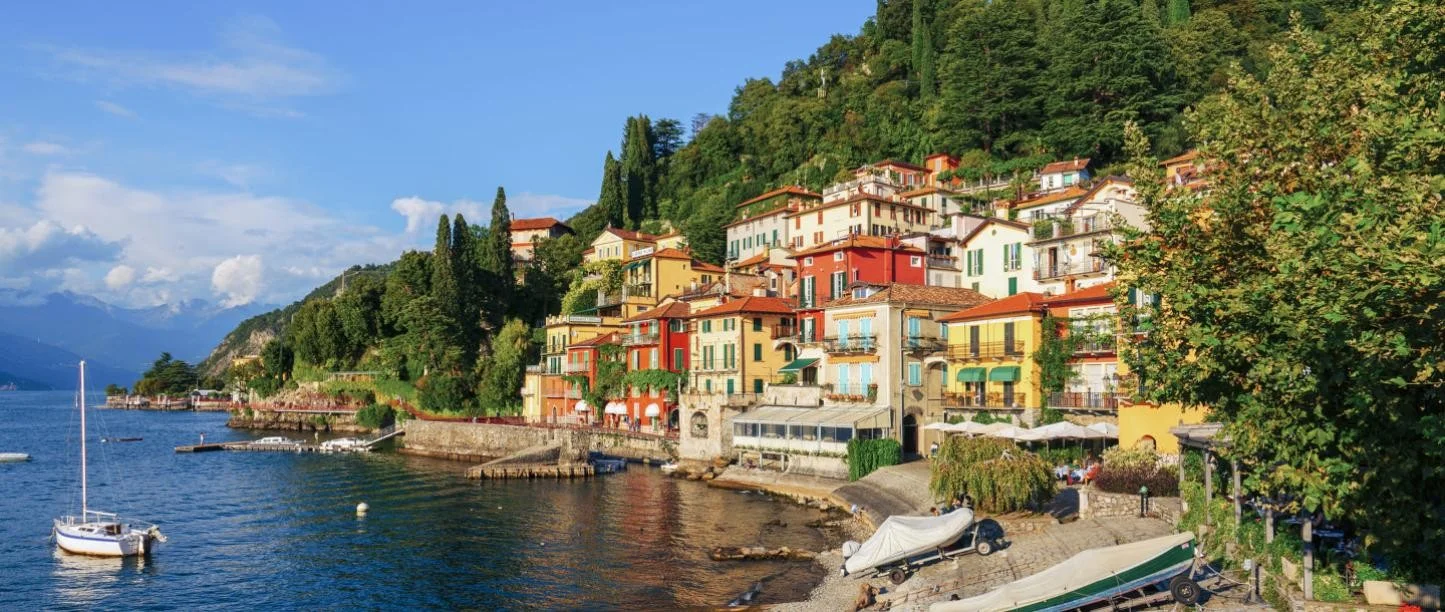
Lake Como versus Liguria defines Italy’s northern luxury property divide, two markets that share low yields, high-net-worth appeal, and capital-preservation positioning, yet deliver fundamentally different lifestyle propositions. Como anchors on alpine lake villa culture with Milan executive access; Liguria stretches along the Mediterranean Riviera from Genoa’s port economy to Portofino’s yacht harbours and Cinque Terre’s cliffside villages.
Neither region rewards yield-focused investors. Lake Como lakefront properties trade €8,000-25,000/m² with gross rental returns of 2-3%, while Liguria’s coastal premium band spans €3,000-10,000+/m² delivering 2-4% yields depending on micro-location and property type. Financial returns concentrate in scarcity-driven appreciation, brand prestige, and portfolio diversification, not monthly cash flow.
This comparison examines investment fundamentals across both markets: pricing tiers, yield mechanics, buyer demographics, short-term rental frameworks, liquidity patterns, infrastructure access, and strategic fit for international purchasers evaluating northern Italy’s twin luxury corridors.
How do yield and appreciation compare between the two?
The yield gap between Lake Como and Liguria is narrow but meaningful for investors who still require some rental income to offset holding costs. Lake Como lakefront gross yields cluster at 2-3%, reflecting extreme purchase premiums relative to achievable nightly rates. A restored 200 m² Bellagio villa purchased at €4 million (€20,000/m²) might generate €80,000-120,000 gross annual short-term rental revenue in peak seasons, translating to 2-3% before management, taxes, and maintenance.
Liguria coastal properties achieve 2-4% gross yields through a wider price spectrum. A San Remo sea-view apartment at €6,000/m² (€480,000 for 80 m²) renting €1,200-1,800 monthly during extended seasons produces roughly 3-4.5% gross. Portofino and Cinque Terre command premiums compressing yields toward Como’s 2-3% range, while Rapallo, Santa Margherita Ligure, and Bordighera offer mid-tier coastal exposure with slightly better income math.
Capital appreciation tells a more differentiated story. Lake Como prime lakefront has recorded 2-4% annual appreciation over the past decade, driven by finite waterfront supply, Milan wealth concentration, and persistent international villa demand. Trophy assets in Bellagio, Cernobbio, and Tremezzina appreciate faster than hillside stock lacking direct lake access.
Liguria appreciation varies by micro-market. Portofino and exclusive Cinque Terre villages track Como-like scarcity premiums at 2-3.5% annually. Broader Riviera markets including San Remo and the Genoa coastal corridor show 1.5-3% appreciation with greater cyclical sensitivity to Italian domestic demand and French Riviera cross-border comparisons.
| Performance Metric | Lake Como (lakefront) | Liguria (coastal premium) |
|---|---|---|
| Gross rental yield | 2-3% | 2-4% |
| Capital appreciation (annual) | 2-4% (prime lakefront) | 1.5-3.5% (location-dependent) |
| Total return potential | 4-7% | 3.5-7% |
| Peak season occupancy | 55-70% | 60-75% |
| Income predictability | Low-Moderate | Moderate |
Risk-adjusted returns favour capital-preservation buyers accepting sub-3% net yields after 21% cedolare secca taxation, 15-20% management fees, and €8,000-25,000 annual maintenance on larger villas. A Como lakefront property yielding 2.5% gross with 65% occupancy produces under 1.6% gross effective income, often below 0.5% net after deductions. Liguria mid-tier coastal stock performs marginally better on income but remains fundamentally appreciation-driven.
For investors comparing northern Italy luxury against established alternatives, Tuscany Property Investment Guide documents a parallel market at lower absolute prices with comparable yield compression on prime stock.
How do entry prices and accessibility compare in Lake Como versus Liguria?
Como is more expensive and better connected. Stock near €5,500 per sqm sits 60-75 minutes from Malpensa, 50-60 from Linate and 30 from Lugano’s private terminal. Rapallo on the Ligurian coast trades nearer €3,800 with one airport at 35-45 minutes. The premium buys aviation access as much as it buys the lake.
Lake Como pricing reflects extreme waterfront scarcity. Direct lakefront villas and apartments in prime municipalities trade €8,000-25,000/m², with Bellagio, Cernobbio, and Laglio commanding the upper band. Hillside properties with lake views but no waterfront access trade €4,000-8,000/m², still premium, but materially below frontage stock. Interior Valle Intelvi or upper lake towns (Domaso, Gravedona) offer €2,500-4,500/m² entries lacking the global branding that drives HNW demand.
Meaningful Como lakefront investment typically requires €1.5-3 million for restored villas and €800,000-1.5 million for quality lake-view apartments. Trophy estates exceeding €10-30 million represent a separate ultra-luxury segment with bespoke liquidity dynamics, not comparable to standard investor entry points.
Liguria’s coastal premium band spans €3,000-10,000+/m² across a longer coastline with more price tiers. Portofino village properties exceed €12,000-18,000/m² for harbour-front stock. Cinque Terre villages (Monterosso, Vernazza, Riomaggiore) trade €8,000-14,000/m² for restored units with sea views. San Remo, Rapallo, and Santa Margherita Ligure offer €4,000-8,000/m² for quality coastal apartments. Genoa’s revived waterfront (Boccadasse, Nervi) and hinterland towns provide €2,500-5,000/m² alternatives with urban connectivity.
| Cost Category | Lake Como (lakefront) | Liguria (coastal premium) |
|---|---|---|
| Prime €/m² range | €8,000-25,000 | €3,000-10,000+ |
| Hillside/secondary €/m² | €4,000-8,000 | €2,500-5,000 |
| Entry villa (200 m²) | €1.6-5 million+ | €600,000-2 million |
| Renovation (historic) | €2,000-3,500/m² | €1,500-2,800/m² |
| Transaction costs | 8-12% | 8-12% |
| Annual holding costs | €15,000-40,000+ | €8,000-25,000 |
Financial accessibility clearly favours Liguria for investors deploying €500,000-1.5 million who still want northern coastal exposure. Lake Como lakefront at comparable quality typically requires €2 million minimum, positioning the market for ultra-HNW and family-office capital.
- Como lakefront is priced on scarcity; Ligurian sea-view stock is priced on condition and floor level.
- Budget between 10% and 15% all-in on a non-resident second home before setting 2 asking prices side by side.
- Check the lift certificate and 3 years of spese history on any pre-1980 Ligurian block.
Which buyer profiles fit Lake Como versus Liguria?
Como typically suits foreign buyers seeking a trophy asset where scarcity supports value and the binding question is what the deed conveys. Liguria suits buyers wanting a coastal apartment at a materially lower entry, who can accept ageing condominium stock, recurring extraordinary works votes, and protected-area rules that constrain what may be altered externally.
| Check | Lake Como versus Liguria action |
|---|---|
| Pricing | Three OMI-quartiere closed sales |
| Compliance | Visura catastale and conformità edilizia |
| Tax path | Cedolare secca election at RLI registration |
EU citizens buy on equal terms with Italian nationals, while non-EU buyers from reciprocity countries need a codice fiscale and follow the same notary-led route.
Lake Como and Liguria attract overlapping but distinct high-net-worth buyer segments, reflecting different lifestyle narratives and geographic connections.
Lake Como buyers (70-75% lifestyle/HNW, 15-20% Milan-corridor executives, 10-15% trophy collectors): American and British buyers dominate international Como purchases, followed by Swiss, German, and increasingly Gulf-state purchasers seeking European villa privacy. Primary motivations include lake villa culture, Milan business corridor access (45-60 minutes to city centre), celebrity-adjacent market positioning, and multi-generational family estate planning.
Typical Como buyer profile: Age 50-70, net worth €5-50 million+, allocating €2-15 million to Italian property, prioritising privacy, architectural heritage, and waterfront scarcity over rental income. These buyers often hold 10-20 year horizons, accepting minimal cash flow in exchange for capital preservation and lifestyle utility.
Success on Como requires understanding waterfront concession regulations (concessione demaniale), boat dock permitting, and municipality-specific building restrictions on historic facades. Properties without direct lake access trade at 40-60% discounts to frontage stock, a critical pricing distinction inexperienced buyers miss.
Liguria buyers (55-60% lifestyle coastal, 25-30% Italian domestic, 15-20% yield-aware HNW): French, German, Dutch, and British buyers lead international Liguria demand, with strong Italian domestic flows from Turin, Milan, and Piedmont seeking Mediterranean weekend properties. French Riviera cross-shoppers compare Portofino pricing against Saint-Tropez and Cannes, often finding Liguria value at equivalent prestige tiers.
Typical Liguria buyer profile: Age 45-65, net worth €2-20 million, allocating €500,000-3 million, seeking Mediterranean coast lifestyle with Genoa airport and port connectivity. Buyers often balance personal use (April-October) with selective short-term rental during peak weeks.
Success on Liguria requires micro-location precision. Portofino and Cinque Terre command scarcity premiums but face stricter rental caps and limited renovation flexibility in UNESCO-buffered zones. San Remo and the western Riviera offer more operational freedom with established casino tourism and conference demand supporting shoulder-season occupancy.
What short-term rental rules apply on each coast?
Compliance requires the same three things in both places: CIN registration, the comune’s permission for tourist use, and a condominium regolamento that does not forbid it. Foreign buyers should confirm all 3 for the specific address before the caparra, since any one of them can block the intended use.
Lake Como and Liguria STR operators both need CIN codes, municipal SCIA reviews, Alloggiati Web reporting, and lakefront or Albaro regolamento caps before modeling July-August nightly rates.
Both regions operate within Italy’s national short-term rental framework, but municipal enforcement and waterfront-specific rules create distinct compliance landscapes.
Lake Como regulatory environment: National CIN (Codice Identificativo Nazionale) registration applies to all tourist rentals. Como, Bellagio, Menaggio, and Lecco municipalities require SCIA (Segnalazione Certificata di Inizio Attività) with tourism classification. Lakefront residential zones restrict continuous tourist activity, many buildings permit short-term rental only outside pure residential condominiums.
Waterfront properties may require additional concessione demaniale review when guest access involves shared lake paths or private docks. Daily rental caps are uncommon but building-level restrictions effectively limit investor operations in prime lakefront condominiums. Cedolare secca flat tax at 21% for non-residents applies universally.
Bellagio and Menaggio enforce moderate oversight with tourist tax collection (€1.50-2.50 per person per night) and periodic compliance inspections. Hillside municipalities generally permit STR with standard CIN/SCIA compliance.
Liguria regulatory environment: CIN and SCIA requirements apply across all coastal comuni. Portofino restricts new tourist accommodation licences in the historic village core, a critical constraint for investors assuming rental income from village-centre purchases. Cinque Terre municipalities cap visitor flows at the municipal level, indirectly constraining STR expansion through parking, access, and building-use policies.
San Remo, Rapallo, and Santa Margherita maintain more permissive STR frameworks with established tourism infrastructure supporting year-round rental platforms. Genoa’s coastal neighbourhoods (Boccadasse, Albaro) increasingly regulate STR in residential palazzi but remain more accessible than Como lakefront condominiums.
| STR Factor | Lake Como | Liguria |
|---|---|---|
| CIN requirement | Yes, all properties | Yes, all properties |
| Municipal licensing | SCIA + zone restrictions | SCIA; Portofino/Cinque Terre caps |
| Lakefront/coastal limits | Building-level residential bans | Village-level licence limits |
| Tourist tax | €1.50-2.50/night | €1.50-3/night |
| Cedolare secca (non-resident) | 21% | 21% |
| Enforcement level | Moderate-High (prime zones) | Moderate (varies by comune) |
Regulatory due diligence is non-negotiable in both markets. Investors should verify STR eligibility before purchase, not after, particularly for lakefront condominiums in Como and historic village properties in Portofino.
- CIN registration is required nationally before a unit is advertised for tourist use.
- The comune sets tourist-use rules, and the condominium regolamento can forbid the use regardless.
- Short-let income is taxed at 21% on the first unit and 26% on the second.
How does resale liquidity compare in Lake Como versus Liguria?
Como’s resale pool is international but narrow, so pricing at the top is sentiment-sensitive and sales can take time. Liguria’s is broader and more domestic, which typically means faster transactions at lower price points and a market far less exposed to a single category of foreign buyer or to one weak season.
| Check | Lake Como versus Liguria action |
|---|---|
| Pricing | Three OMI-quartiere closed sales |
| Compliance | Visura catastale and conformità edilizia |
| Tax path | Cedolare secca election at RLI registration |
Como’s lakefront resells slowly and to a narrow international pool, at €8,000-25,000 per sqm where concession rights and retaining walls both sit outside the deed. Liguria’s Riviera coast at €3,000-10,000 has a broader mid-market and moves faster, on yields of 2-4% against Como’s 2-3%. Work from three OMI-quartiere closed sales in the same micro-district rather than portal asking averages, read alongside the protected-area position and who is liable for retaining walls. Have an independent avvocato read the visura catastale, the conformità position and three years of condominium spese before the compromesso, with particular weight on the protected-area position and who is liable for retaining walls.
Lake Como liquidity: Global brand recognition, reinforced by decades of celebrity ownership and Milan’s financial centre proximity, creates consistent international buyer demand for prime lakefront stock. Trophy villas in Bellagio and Cernobbio sell within 12-18 months when priced within 5-10% of market value. Hillside properties without lake access face extended timelines (18-30 months) and often require 10-15% price adjustments.
The buyer pool is narrower but deeper at the ultra-luxury tier. Properties above €5 million attract family offices, sovereign wealth adjacent purchasers, and multi-property Italian villa collectors. Below €1.5 million, liquidity thins as product stock lacks the trophy characteristics driving global demand.
Liguria liquidity: Coastal liquidity varies dramatically by micro-market. Portofino village properties sell within 12-24 months to international buyers seeking Italian Riviera prestige at discounts to French alternatives. Cinque Terre units attract lifestyle buyers but face renovation and access constraints limiting the buyer pool. San Remo and western Riviera markets show moderate liquidity (18-30 months) with stronger Italian domestic participation.
Genoa’s improving waterfront districts demonstrate emerging liquidity as urban regeneration attracts younger domestic buyers and investors, a segment distinct from Como’s villa culture. Secondary Liguria towns inland from the coast (Dolceacqua, Finalborgo) remain illiquid for international resale, requiring Italian buyer targeting.
Pricing stability: Both markets demonstrated resilience during 2020-2022, with prime stock holding value better than secondary locations. Como lakefront prices showed minimal decline (0-5%) before recovering strongly 2022-2025 as Milan financial sector growth and international travel resumption accelerated demand. Liguria’s top-tier coastal villages matched this pattern; secondary coastal stock experienced 5-10% softening before stabilising.
- Como’s pool is international but narrow, so sales at the top are sentiment-sensitive.
- Liguria’s is broader and domestic, which typically means faster sales at lower price points.
- Capital gains are taxable on a sale within 5 years in either region.
How does infrastructure compare on Lake Como versus Liguria?
Como is served by three airports: Malpensa at 60-75 minutes, Linate at 50-60, and Lugano for private aviation at 30, which is what supports stock near €5,500 per sqm. Liguria’s Rapallo sits 35-45 minutes from Genoa Cristoforo Colombo at nearer €3,800, with one airport and less private traffic.
| Link | Lake Como | Liguria coast |
|---|---|---|
| Primary airport | Malpensa 60-75 min | Genoa 35-45 min to Rapallo |
| Milan CBD commute | 45-60 min by rail | 90-120 min AV to Genoa |
| Private aviation | Lugano 30 min | Nice 90 min (west Liguria) |
| Tenant profile | Finance weekenders | Coastal lifestyle + port workers |
Commute and airport access on Lake Como and Liguria property shapes tenant pools: walkable services and rail links command premium rents versus car-only fringe stock on identical sqm bands.
Lake Como infrastructure: Milan Malpensa Airport (60-75 minutes to Como) and Milan Linate (50-60 minutes) provide global connectivity. Lugano Airport in Switzerland offers additional private aviation access 30 minutes from Menaggio. Milan’s financial, fashion, and corporate infrastructure creates year-round demand spillover, executives maintaining Como villas for weekend and seasonal use.
Lake ferry networks, private boat moorings, and lakeside promenades define daily life. International schools in Como and Milan support family relocations. Healthcare infrastructure is excellent through Milan’s hospital network. High-speed rail from Milano Centrale reaches Como in 40 minutes.
Property services, architects, restoration specialists, landscape designers, concentrate around Como, Cernobbio, and Bellagio with established English-speaking firms serving international clients. Villa management companies operate at premium fee levels (18-25% of rental revenue) reflecting service intensity.
Liguria infrastructure: Genoa Cristoforo Colombo Airport (30-45 minutes to Portofino, 20 minutes to Genoa centre) and Nice Côte d’Azur Airport (90 minutes to western Liguria) provide international access. Genoa’s port, Italy’s largest commercial harbour, supports yacht culture and maritime services along the coast.
Autostrada A10 (Riviera dei Fiori) and A12 (Riviera di Levante) connect the full coastline. Genoa’s urban regeneration brings restaurants, cultural venues, and tech-sector growth creating year-round city demand distinct from seasonal coastal tourism.
Coastal property services concentrate in San Remo, Rapallo, and Genoa with contractor networks experienced in cliffside construction, humidity management, and seismic retrofitting. Marina infrastructure from Portofino to Imperia supports yacht-owning buyers, a lifestyle dimension Como provides through lake boating rather than open-sea access.
| Infrastructure Factor | Lake Como | Liguria |
|---|---|---|
| Nearest major airport | Milan Malpensa (60-75 min) | Genoa (20-45 min) |
| Financial centre proximity | Milan (40-60 min) | Genoa (urban); Milan (90-120 min) |
| International schools | Como + Milan | Genoa + Nice corridor |
| Marina/yacht culture | Lake boating | Mediterranean marinas |
| English-speaking services | Established | Established (coastal towns) |
| Year-round livability | Moderate (lake seasonality) | Moderate-High (Genoa urban) |
Which strategy suits Lake Como and which suits Liguria?
Strategy on Como is capital preservation with a short letting season; on the Ligurian coast it is closer to a yield play with heavier maintenance. Foreign buyers should size each on annual occupancy rather than peak-week rates, then subtract IMU at 0.86% to 1.06% and condominium spese.
- Capital preservation and trophy asset positioning dominate return requirements
- Budget exceeds €2 million for meaningful lakefront or premium lake-view exposure
- Milan business corridor access adds personal or corporate utility
- Villa architecture, lake privacy, and multi-generational estate planning drive the purchase
- Holding horizon exceeds 10 years to capture scarcity appreciation
- Rental income is secondary, under 2% net yield is acceptable
- Buyer values global brand recognition (Bellagio, Cernobbio) for resale depth
Optimal Como strategies target direct lakefront in established municipalities, prioritise properties with existing concessione demaniale and boat access, and engage local notaio and architect teams before commitment. Hillside properties work for lifestyle buyers accepting liquidity discounts. Explore detailed market mechanics in the Lake Como Property Investment Guide and municipality context in Como Area Guide and Bellagio Area Guide.
Choose Liguria when:
- Mediterranean coast lifestyle and Riviera tourism exposure matter
- Budget €500,000-2 million requires quality coastal stock without Como lakefront premiums
- Slightly higher yield potential (2-4%) helps offset holding costs
- Genoa urban regeneration or yacht marina culture adds lifestyle utility
- Buyer wants diversification within northern Italy alongside Tuscany or Lombardy holdings
- French Riviera comparison shopping favours Italian pricing at comparable coastal prestige
- Holding horizon 7-12 years captures coastal appreciation with personal use value
Optimal Liguria strategies prioritise San Remo, Santa Margherita, or Rapallo for balanced coastal exposure; Portofino only for trophy buyers accepting rental restrictions; Genoa waterfront for urban-coastal hybrid plays. Verify STR eligibility and building restrictions in Cinque Terre villages before any commitment.
Portfolio context: Both markets suit investors already holding Italy Property Investment Guide core positions who want northern luxury diversification. The Best Regions to Invest in Italy Property 2026 overview places Como and Liguria in the capital-preservation tier alongside prime Tuscany, distinct from Puglia and Sicily yield markets.
What are the pros and cons of Lake Como versus Liguria?
Como gives foreign buyers constrained supply and international recognition, against a thin resale market that is sensitive to sentiment. Liguria gives a lower entry and a broader domestic pool, against ageing stock where lift, façade and terrace programmes arrive as extraordinary assessments voted by the assembly.
Como offers foreign buyers international recognition and constrained supply, at the cost of a thin, sentiment-sensitive resale market. Liguria offers a lower entry and a broader domestic buyer pool, at the cost of older stock where lift, façade and terrace programmes recur as extraordinary assessments.
Lake Como versus Liguria comparisons require matching €450,000-750,000 sea-view tickets, CIN compliance costs, and winter void assumptions before allocating between Lombardy lakefront and Genoa-Albaro urban-coastal stock.
- Finite lakefront scarcity supporting long-term appreciation
- Global villa brand recognition and deep ultra-HNW buyer pool
- Milan executive corridor access (40-60 minutes)
- Exceptional liquidity for trophy lakefront stock (12-18 months)
- Lake villa culture with privacy and alpine-lakeside aesthetic
- Established international service infrastructure
Lake Como challenges:
- Lowest yields in Italy (2-3% gross lakefront)
- Extreme entry pricing (€8,000-25,000/m² lakefront)
- Waterfront concession and building-use complexity
- STR restrictions in prime lakefront condominiums
- Seasonal demand concentration (May-September peak)
- Hillside stock lacks liquidity of frontage properties
Liguria advantages:
- Broader coastal price tiers (€3,000-10,000+/m²)
- Marginally better yields (2-4%) on mid-tier coastal stock
- Mediterranean lifestyle with yacht and beach culture
- Genoa airport proximity and port city urban energy
- French Riviera alternative at lower absolute pricing
- Diverse micro-markets enabling portfolio layering within one region
Liguria challenges:
- Sharp micro-location risk (Portofino vs secondary towns)
- Cinque Terre and Portofino rental and renovation restrictions
- Seismic and cliffside construction complexity on coastal plots
- Lower global brand recognition than Lake Como for trophy assets
- Seasonal tourism dependence outside Genoa urban core
- Inland and secondary coastal stock remains illiquid internationally
What is the regional verdict for Lake Como versus Liguria?
Como is the scarcity play and Liguria the access play, and neither substitutes for the other. Foreign buyers choosing Como are paying for a supply-constrained shoreline; those choosing Liguria are paying materially less per sqm and taking on ageing condominium stock and protected-area works rules.
| Mandate | Favor when |
|---|---|
| Income-first | Higher gross yield corridor on Lake Como versus Liguria |
| Lifestyle exit | Stronger foreign resale depth on trophy tickets |
| Hold under 5 years | Faster rogito liquidity and tenant depth |
Neither market suits yield-first investors. Both demand clear-eyed acceptance that rental income covers holding costs at best, while appreciation, lifestyle utility, and portfolio diversification deliver the real return. The choice hinges on lifestyle preference, budget scale, and geographic connectivity requirements.
Ultra-HNW preservation buyers (€2-15 million, 10+ year horizon): Lake Como lakefront typically outperforms on scarcity, global branding, and Milan spillover. Bellagio and Cernobbio frontage offers the strongest capital preservation profile in northern Italy outside prime central Milan.
HNW coastal lifestyle buyers (€500,000-3 million, 7-12 year horizon): Liguria provides more accessible entry with Mediterranean coast exposure and slightly better income math. San Remo and Rapallo balance coastal prestige with operational flexibility.
Diversified Italian portfolio builders: Combining Como lake-view property (preservation anchor) with Liguria coastal apartment (Mediterranean exposure and personal use) creates northern Italy luxury diversification without concentrating micro-location risk.
Expected return illustration for a €3 million Como lakefront villa: 2.5% gross yield (€75,000) minus 21% cedolare secca, 20% management, and €20,000 maintenance produces near-zero net income. Over 10 years, 3% annual appreciation adds approximately €1 million in capital gain, the primary return driver. A €900,000 Liguria coastal apartment at 3.5% gross yield with 3% appreciation delivers similar total-return mechanics at lower absolute deployment.
For comprehensive Italy context, see Italy Property Investment Guide. For regional ranking across all Italian markets, consult Best Regions to Invest in Italy Property 2026. Compare adjacent northern lifestyle markets via Tuscany Property Investment Guide.
Lake Como versus Liguria is ultimately a lifestyle and capital-preservation decision, not a yield optimisation problem. Both markets reward patient HNW capital that values Italian northern identity, alpine lake villa culture on one hand, Mediterranean Riviera coast on the other, with realistic expectations about income, liquidity timelines, and the regulatory care these trophy markets demand. Insider tip: Model both cities with identical capital and hold period before choosing, per sqm gaps often reverse after IMU, cedolare secca, and vacancy assumptions.
Lake Como versus Liguria underwriting from Italian Estate compares Lombardy lake prestige against Riviera port-city value for non-resident buyers allocating €400,000-2,000,000 in Q2 2026. Como lakefront trades €8,000-25,000 per sqm on Bellagio and Cernobbio trophy stock with gross yields near 2-3% before IMU and condominium STR bans on prime frontage buildings. Liguria Genoa Albaro and Rapallo corridors average €2,200-3,400 per sqm with Q1 2026 rent growth near 6.4% supporting 4-5% gross on sub-€400,000 furnished leases and Milan-Genoa rail under 90 minutes. Non-resident closing stacks run 10-12% on both markets with 9% registration tax and geotechnical survey near €1,500-€3,000 on Liguria hillside tickets versus less frequent soprintendenza filings on Genoa portico stock.
Buyer profile benchmarks show Como drawing Anglo-Saxon, Swiss, and Gulf HNW capital for finite lakefront scarcity and Milan executive links within 40-50 minutes by train while Liguria attracts yield-aware buyers comparing Albaro sea-view resale against Tuscan premiums on per sqm basis. STR rules require CIN on both regions with Como building-level tourist bans more common on residential lakefront condominiums than Rapallo or Santa Margherita Ligure comuni with moderate caps. Italian Estate recommends Como above €1.5M for preservation-first mandates; Liguria for balanced HNW allocation when 4-5% gross helps offset IMU and 21% cedolare secca on licensed furnished leases reviewed before spring listing season offers.Underwriting here starts with the visura catastale and the conformità position, then turns to the protected-area position and who is liable for retaining walls.
- Como is the scarcity position: supply-constrained shoreline, thin resale, long hold.
- Liguria is the access position: lower entry per sqm, broader domestic pool, heavier maintenance.
- Either region charges a second home IMU on cadastral value, at a comune rate between 0.86% and 1.06%.
How Do the Two Markets Behave Differently?
These are two different constraint systems rather than two price levels. Foreign buyers on Como are underwriting scarcity and lakefront concession rights, while Liguria’s coastal stock is governed by protected-area rules and by hillside geotechnics that decide whether terrace and access works are permitted at all, which is a question to settle before price rather than after.
| Dimension | Lake Como | Liguria |
|---|---|---|
| Binding constraint | Lakefront concession rights | Protected-area and slope rules |
| Typical stock | Villas and lakefront apartments | Pre-1980 sea-view condominiums |
| Works risk | Concession and heritage clearance | Retaining walls, terraces, façades |
| Approval timeline | Long on protected villas | Commonly 12-18 months inside the Portofino park |
- On Como, ask for the concession document and its expiry rather than the agent’s phrase “private mooring”.
- In Liguria, request 3 years of spese history: lift and façade programmes dominate the carry on older blocks.
- IMU on a second home is 0.86% to 1.06% of cadastral value in both regions, with no primary-residence relief.
Frequently Asked Questions
Liguria coastal markets deliver slightly higher gross yields at 2-4% versus Lake Como's 2-3% lakefront range. Liguria's broader price band (€3,000-10,000+/m²) creates more mid-market rental opportunities in San Remo and Rapallo, while Como lakefront premiums compress yields despite strong demand. Both remain income-secondary, capital-preservation markets.
Lake Como lakefront properties trade €8,000-25,000/m², with meaningful villas starting €1.5-3 million and trophy assets exceeding €10 million. Liguria coastal premiums span €3,000-10,000+/m² depending on micro-location, Portofino and Cinque Terre at the top, Genoa hinterland and secondary Riviera towns lower. Liguria offers wider budget flexibility for HNW buyers.
Lake Como suits buyers prioritizing lake villa culture, Milan executive access, and ultra-exclusive waterfront scarcity. Liguria appeals to Mediterranean coast lifestyle, Riviera yacht tourism, and buyers wanting coastal exposure with Genoa urban connectivity. Both target capital preservation over yield; Como commands higher absolute pricing and global villa prestige.
Both regions require national CIN registration and municipal SCIA compliance. Lake Como municipalities (Como, Bellagio, Menaggio) enforce stricter caps on historic waterfront zones and limit continuous tourist use in residential lakefront areas. Liguria varies by comune, Portofino and Cinque Terre villages impose seasonal caps, while San Remo and Rapallo maintain more permissive frameworks.
Lake Como draws American, British, Swiss, and Gulf HNW buyers seeking villa privacy, Milan proximity, and celebrity-adjacent lake branding. Liguria attracts French Riviera cross-shoppers, German and Dutch coastal lifestyle buyers, and Italian domestic purchasers from Piedmont and Lombardy seeking Mediterranean exposure. Como skews ultra-luxury; Liguria offers broader coastal tiers.
Lake Como maintains exceptional liquidity for trophy lakefront villas through global brand recognition and limited waterfront supply, prime assets in Bellagio and Cernobbio sell within 12-18 months when priced correctly. Liguria liquidity varies sharply: Portofino and Cinque Terre hold premium demand, while secondary Riviera towns require 18-30 month timelines. Both outperform rural southern Italy on exit depth.
Lake Como offers stronger scarcity premiums on finite lakefront frontage, Milan economic spillover, and decades of international villa demand supporting 2-4% annual appreciation on prime stock. Liguria provides diversified coastal exposure with slightly better yield headroom (2-4%) and lower absolute entry at non-trophy addresses. For pure preservation, Como lakefront wins; for balanced northern coastal exposure, Liguria adds optionality.
Get an Italy property shortlist
Tell us your budget and region (Tuscany, Lake Como, Puglia, Milan, Sardinia). We reply within one business day with options matched to your goals.