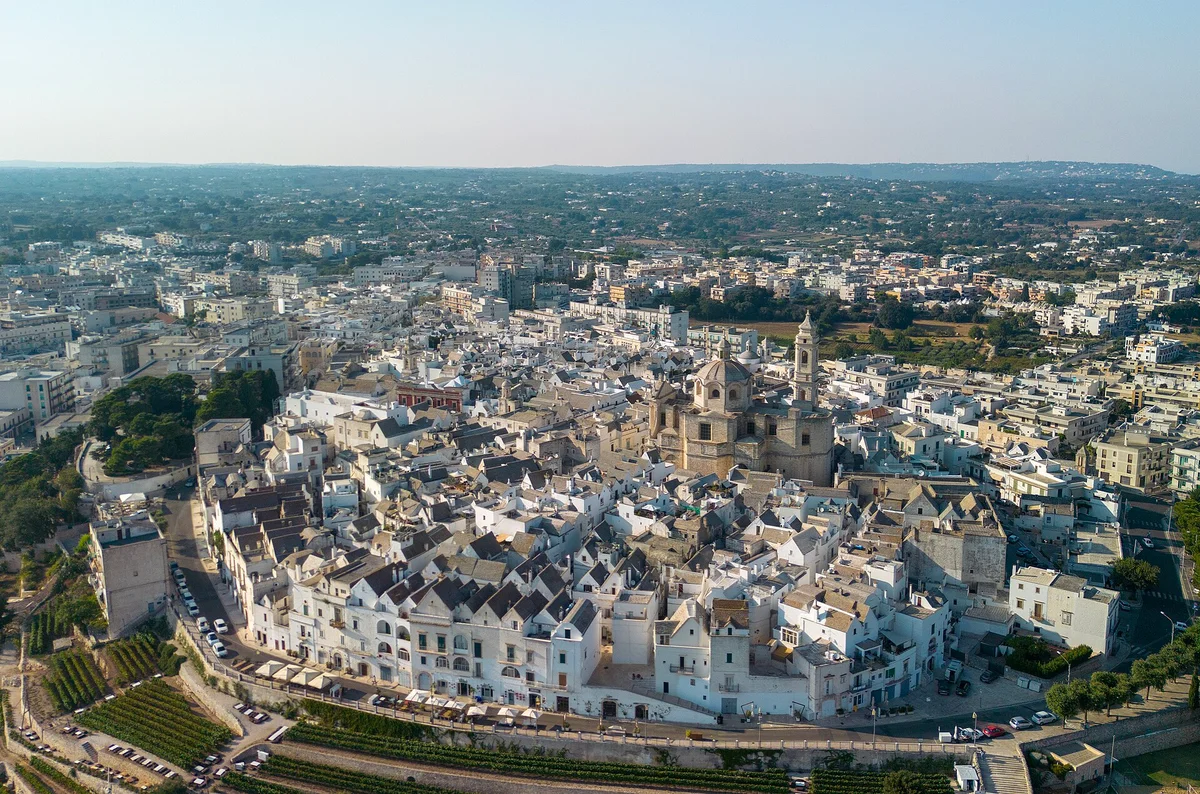
Quick answer: Puglia offers higher rental yields (5-8% vs 4-7%) and lower entry prices (€80k-150k vs €200k-400k) but Tuscany provides better liquidity and established luxury positioning. Flagship compare: Ostuni area trulli versus Florence area trophy stock. Read Puglia guide and Tuscany guide.
How do Puglia vs Tuscany compare at a glance?
Puglia returns 5-8% gross short-let on tickets of €80,000-400,000; Tuscany returns 4-7% on €200,000-800,000. German buyers take 35-40% of southern enquiry, Americans dominate the Tuscan pool. On identical €250,000-400,000 capital the decision is not really about yield: it is about whether you want the higher income now or the deeper, faster resale market later, because Tuscany has consistently offered the second and Puglia the first.
| Metric | Puglia | Tuscany |
|---|---|---|
| Gross yield band | 5-8% STR | 4-7% mixed |
| Entry renovation | €80k-150k | €200k-400k |
| Restored mid-market | €150k-400k | €400k-800k |
| Capital appreciation | 4-12% volatile | 3-5% steady |
| Occupancy STR | 60-75% | 70-85% |
| Foreign liquidity | Developing | Established |
| Top foreign buyer | Germany 35-40% | US 30-35% |
- Choose Puglia for yield optimization and authentic trulli or coastal STR on sub-€400,000 tickets.
- Choose Tuscany for capital appreciation, wine country lifestyle, and faster foreign resale above €400,000.
- Read best regions 2026 guide before southern-northern allocation.
How do entry prices compare in Puglia versus Tuscany?
Puglia renovation projects start at €80,000-150,000 against €200,000-400,000 in Tuscany on 2026 portal data; prime Ostuni trulli run €150,000-350,000 while comparable Chianti stock sits at €400,000-600,000. The gap is roughly two to one across every tier. Spring asking prices overshoot winter closings by 10-15% on €250,000 tickets in both regions, so take three closed sales per micro-market before making an offer.
| Ticket type | Puglia indicative | Tuscany indicative |
|---|---|---|
| Value renovation | €80k-150k inland | €200k-350k secondary |
| Coastal / trulli mid | €150k-350k | n/a direct compare |
| Chianti / Val d’Orcia | n/a | €400k-800k restored |
| Restoration capex | €30k-80k typical | €50k-150k typical |
| Closing cost band | 7-12% | 8-13% |
- A €250,000 budget buys restored Ostuni trulli or secondary Tuscany farmhouse needing selective renovation.
- Model trulli restoration at €800-1,500 per sqm before comparing total project cost across regions.
- Cross-read Valle d’Itria area and Siena area for micro-market depth.
How do rental yields compare in Puglia versus Tuscany?
Puglia short-let delivers 5-8% gross, with Ostuni’s peak summer weeks pushing the better-bought stock to the top of that range. Tuscany’s mixed income model reaches 4-7%, with Chianti farmhouses at 4-6% but a far longer shoulder season. Model the net after cedolare secca: 21% on a long lease, 26% on a second short-let unit, because Puglia’s November-to-April void frequently reverses the headline gap entirely.
| Strategy | Puglia gross | Tuscany gross | Best region |
|---|---|---|---|
| Coastal STR | 6-8% peak | 4-6% coast | Puglia yield |
| Trulli cultural STR | 5-7% annual | n/a | Puglia unique |
| Chianti farmhouse STR | n/a | 4-6% | Tuscany brand |
| Academic long lease | 3-4% Lecce | 3-3.5% Florence | Tuscany stability |
| Luxury villa STR | 5-7% Salento | 5-7% Val d’Orcia | Comparable peak |
Puglia STR and trulli income economics
Take a restored trullo bought at €220,000 producing €13,600 of annual short-let gross at 65% occupancy across a May-to-October season: that is 6.2% before IMU and before cedolare secca at 26% on a second unit. German guests, at 35-40% of enquiry, drive most of the booking conversion on Valle d’Itria stock. The figure holds only while occupancy does, and occupancy here is a six-month proposition.
- Model November-April void honestly before Puglia coast-only STR pro forma on €200,000 tickets.
- Verify CIN registration and regional codice identificativo before first booking on trulli inventory.
- Compare net yield against Tuscany Chianti farmhouse at 4-5% gross on €450,000 restored ticket.
Tuscany wine country and urban income economics
A Chianti farmhouse at €480,000 producing €28,000 of annual short-let gross at 75% occupancy returns 5.8% before IMU: a lower headline than Puglia, on a longer season. Tuscany’s winter shoulder demand, driven by culture and city breaks rather than beaches, is what closes the gap on the annual number. American lifestyle buyers account for 30-35% of enquiry, and they buy for the hold rather than the yield.
- Budget €50,000-150,000 restoration on Tuscany farmhouses versus €30,000-80,000 on comparable Puglia stock.
- Confirm municipal STR day limits in Florence UNESCO zones before urban STR pro forma on €400,000+ tickets.
- Default to long lease September-May in Florence when UNESCO STR license path uncertain.
How do STR regulations compare in Puglia versus Tuscany?
The regulatory gap is now wide and moving further apart. Puglia keeps a relatively liberal position: CIN registration and tourist tax of €1-3 per person per night. Tuscany layers municipal limits on top, including Florence’s ban on new historic-centre licences, extended city-wide in May 2026, and 120-180 day caps in several comuni. Red flag checklist flags agents marketing Florence centro STR.
| Factor | Puglia | Tuscany |
|---|---|---|
| Licensing difficulty | Low-moderate | Moderate-high |
| Annual rental day limits | Generally unlimited | Often 120-180 days |
| Tourist tax | €1-3/night | €2-5/night |
| Florence UNESCO | n/a | New license bans |
| Enforcement level | Low-moderate | Moderate-high |
| Registration timeline | 30-60 days | 30-90 days |
- Confirm CIN and municipal STR path before Puglia summer pro forma on coastal tickets from €150,000.
- Verify exact Florence address against UNESCO STR policy before deposit on Oltrarno inventory.
- Cross-read Italy holiday let licensing before STR allocation in either region.
Which market offers better resale liquidity in Puglia versus Tuscany?
Chianti stock clears in 6-12 months on 2026 portal data, supported by an American buyer pool at 30-35% of enquiry. Ostuni trulli take 12-18 months, and inland Puglian comuni can take 18-36. That difference compounds: stress-test a seven-year exit with 3-5% agent commission and IMU paid throughout the hold before treating a €80,000 Puglian entry as the cheaper of the two.
| Region | Prime exit period | Secondary exit | Buyer pool |
|---|---|---|---|
| Tuscany Chianti | 6-12 months | 12-18 months | US, UK, German luxury |
| Tuscany Florence edge | 9-15 months | 12-18 months | Lifestyle + academic |
| Puglia Ostuni trulli | 12-18 months | 18-24 months | German, UK cultural |
| Puglia inland value | 18-36 months | 24-36 months | Restoration specialists |
- Price Tuscany tickets to three winter closed sales before spring wine tourism listing peaks.
- Attach engineer certificates and CIN history to Puglia trulli resale packs for German enquiry conversion.
- Compare exit pools against Sicily vs Puglia compare when southern yield thesis spans regions.
How do transportation links compare in Puglia versus Tuscany?
Puglia runs on Bari and Brindisi, with direct low-cost routes from northern Europe putting the Valle d’Itria and the Salento coast 45-90 minutes from arrivals. Tuscany uses Florence, Pisa and Bologna, with high-speed rail linking Chianti to the city: an infrastructure built for a longer-established luxury market. Buyer.
| Factor | Puglia | Tuscany |
|---|---|---|
| Primary airports | Bari, Brindisi | Florence, Pisa |
| Low-cost carrier depth | Strong from Germany | Moderate |
| AV rail hub | Bari-Lecce line | Florence-Bologna-Rome |
| Coast access | Adriatic + Ionian | Tyrrhenian via drive |
| Management partner pool | Growing | Established |
- Budget property management within 45 minutes of Bari airport before remote Puglia STR underwriting.
- Tuscany buyers leverage established English-speaking service networks for luxury guest expectations.
- Cross-read Italy property investment guide for national context before regional pair.
Which buyer scenarios fit Puglia versus Tuscany?
With €150,000-500,000, the deciding question is operational rather than financial. Puglia yield tickets fail without short-let management capacity on the ground, because the season is short and intense. Tuscany trophy stock fails for anyone who actually needs 6%-plus gross, because it has never produced that. Stress-test seasonal cash flow, restoration capex, and exit buyer pool before choosing.
| Profile | Region | Ticket | Strategy | Target yield |
|---|---|---|---|---|
| Yield STR operator | Puglia trulli | €220,000 | Cultural STR | 6-7% gross |
| Luxury lifestyle | Tuscany Chianti | €520,000 | Wine country hold | 4-6% gross |
| Value restoration | Puglia inland | €120,000 | Renovation play | 5-7% with risk |
| Trophy resale | Tuscany Florence edge | €450,000 | Lifestyle + LT lease | 3-4% gross |
| Dual-region portfolio | Both | €250k + €450k | Yield + liquidity | Blended hold |
- Yield STR operator: German buyer acquires Locorotondo trulli at €165,000 plus €85,000 restoration targeting 6.5% gross STR with local management partner within 45 minutes of Brindisi airport.
- Luxury lifestyle: US buyer purchases Chianti farmhouse at €520,000 primarily for personal use with licensed STR shoulder seasons at 5-6% gross when not in residence.
- Dual-region portfolio: Investor holds Puglia trulli cash flow and Tuscany Chianti appreciation within single Italian allocation reviewed with commercialista before sequential wire transfers.
Should foreign buyers choose Puglia or Tuscany in 2026?
The answer follows the priority, not the region. Puglia wins on gross short-let yield at 5-8% under €400,000, on entry price at €80,000-150,000 for renovation stock, and on trulli scarcity. Tuscany wins on resale speed (6-12 months in Chianti) on wine-country brand depth, and on appreciation that has held at 3-5% across decades.
| If your priority is… | Choose | Why |
|---|---|---|
| Highest gross STR yield | Puglia | 5-8% on sub-€400k |
| Lowest entry ticket | Puglia | €80k-150k renovation |
| Fastest foreign resale | Tuscany | 6-12 months Chianti |
| Wine country lifestyle | Tuscany | Global brand depth |
| Trulli uniqueness | Puglia | UNESCO valley asset |
| Steady appreciation | Tuscany | 3-5% decades proven |
- Run identical net yield model with commercialista before choosing on gross STR headline alone.
- Reject Puglia STR pro forma without November-April void modeling on €200,000 coastal tickets.
- Reject Tuscany renovation estimates below €50,000 on Chianti farmhouses marketed with optimistic yield tables.
Who buys Puglia versus Tuscany property from abroad?
The two regions attract different nationalities for different reasons. German buyers lead Puglia enquiry at 35-40%, targeting trulli authenticity and yield at €120,000-350,000. Americans lead Tuscany at 30-35% and pay above €400,000 for wine-country prestige. British buyers, near 20-25% in both, split between the two theses. Track STR.
| Buyer origin | Puglia signal | Tuscany signal |
|---|---|---|
| Germany | ~35-40% enquiry | ~15-20% wine country |
| UK | ~20-25% both | ~25-30% luxury |
| US | Growing Puglia STR | ~30-35% trophy |
| Scandinavia | ~10-15% trulli | ~8-12% lifestyle |
| Netherlands | ~8-12% value | ~10-12% Chianti |
- Market trulli engineer certificates and UNESCO restoration compliance in German-language Puglia listing packs.
- Target Tuscany spring and autumn windows for US trophy resale enquiry on Chianti and Val d’Orcia stock.
- Set both regions against Italy vs Portugal compare when southern European yield thesis spans countries.
What risks should foreign buyers watch in Puglia and Tuscany?
Five risks apply in both regions and trigger differently in each. Capex overruns start with trullo vault damage in Puglia and farmhouse structure in Tuscany; seasonal void with a winter short-let pro forma against a shoulder-heavy mix; compliance with a missing CIN against Florence’s licence ban. Budget 15-20% restoration contingency on Puglian trulli before underwriting anything.
| Risk | Puglia trigger | Tuscany trigger |
|---|---|---|
| Capex overrun | Trulli vault damage | Farmhouse structural |
| Seasonal void | Winter STR pro forma | Shoulder vs peak mix |
| STR compliance | Missing CIN | Florence license ban |
| Liquidity drag | Inland secondary | Overpriced Chianti |
| Regulatory change | Evolving Puglia policy | UNESCO enforcement |
- Budget 15-20% restoration contingency on Puglia trulli before underwriting net yield on €200,000 total project.
- Confirm Florence STR license on exact address before deposit on €400,000+ urban tickets.
- Model vacancy separately for Puglia November-April and Tuscany academic calendar on identical €300,000 tickets.
What should foreign buyers verify before choosing Puglia or Tuscany?
The diligence differs by region. In Puglia: a structural engineer’s assessment of the trullo vaults, and a cadastral regularisation path for structures that predate the register. In Tuscany: the Soprintendenza filing requirement on any planned centro renovation. In both: the CIN registration path, the IMU cadastral band, and whether the cedolare secca election will be 21% on a long lease or 26% on a second short-let unit.
| Document | Puglia priority | Tuscany priority |
|---|---|---|
| Static engineer cert | Trulli vault essential | Farmhouse structural |
| CIN registration | Before STR marketing | Before STR marketing |
| Cadastral regularization | Ancient trulli | Standard urban |
| Soprintendenza filing | UNESCO landscape | Centro renovation |
| Fixed restoration contract | Capex control | Farmhouse scope |
| Management agreement | Remote STR essential | Luxury guest standards |
- Model net yield after IMU and cedolare secca at 21% or 26% with commercialista for both regions.
- Cross-read Puglia guide and Tuscany guide before final offer.
- Independent avvocato review on seller declarations and cadastral consistency in both regions.
Next step: request a curated shortlist for Puglia and Tuscany options. Insider tip: Model both regions with identical capital and hold period before choosing, per sqm yield gaps often reverse after IMU, cedolare secca at 26% STR, and Puglia winter void assumptions.
Puglia versus Tuscany yield underwriting from Italian Estate compares southern STR cash flow against northern luxury mixed income for non-resident buyers allocating €150,000-600,000 capital in Q2 2026. Puglia coastal and trulli STR delivers 5-8% gross on €150,000-400,000 tickets with Ostuni peak summer reaching 6-8% at 75-80% occupancy for German guests at 35-40% enquiry share while a €220,000 trulli at €32,000 annual gross equals 6.2% before IMU and cedolare secca at 26%. Tuscany Chianti farmhouses achieve 4-7% gross on €400,000-800,000 restored stock at 70-85% occupancy with US buyers at 30-35% share supporting 6-12 month prime resale versus Puglia secondary comuni at 18-36 months. Net spreads fall 200-300 basis points below Puglia gross after 20-25% management fees and November-April void omitted from agent pro forma reviewed with commercialista before wire authorization.
Transaction benchmarks for foreign property purchases in Puglia and Tuscany typically range from 7-13% of purchase price combining 9% registration tax on second homes, notary fees near €3,000-€6,000, plus restoration capex of €800-1,500 per sqm on Puglia trulli and €50,000-150,000 on Tuscany farmhouses not included in acquisition closing costs. EU citizens purchase freely with codice fiscale within 2-4 weeks while reciprocity-country buyers follow standard rogito with avvocato review on Puglia cadastral regularization for ancient trulli and Tuscany soprintendenza filings on UNESCO centro renovations before interior capex commitments. CIN registration remains mandatory before STR marketing in both regions with Puglia regional codice identificativo completing within 30-60 days and Tuscany municipal STR permits requiring 30-90 days in comuni with active enforcement including Florence historic center license restrictions reviewed before summer pro forma on tickets above €200,000.
Frequently Asked Questions
Puglia typically delivers higher rental yields of 5-8% compared to Tuscany's 4-7%. Puglia's lower property prices and strong vacation rental demand, especially in coastal areas and trulli regions, create superior yield potential despite Tuscany's premium positioning.
Puglia entry prices start from €80,000-150,000 for renovation projects, while Tuscany begins around €200,000-400,000. Restored properties in Puglia range €150,000-400,000 versus Tuscany's €400,000-800,000 for comparable quality and location.
Puglia favors yield-focused investors with lower entry costs and higher returns. Tuscany suits capital appreciation investors comfortable with premium pricing. Puglia offers emerging market potential, while Tuscany provides established luxury positioning.
Both regions allow short-term rentals but Tuscany has stricter municipal regulations in Florence and historic centers. Puglia maintains more liberal STR policies, especially in emerging markets. Both require tourist tax collection and CIN registration.
Puglia attracts yield-focused investors, Germans seeking value at 35-40% enquiry share, and younger buyers wanting authentic trulli experiences. Tuscany draws luxury investors, Americans at 30-35% share, British buyers prioritizing prestige, and wine country lifestyle holders.
Tuscany maintains superior liquidity due to established international demand and brand recognition with prime Chianti stock clearing 6-12 months. Puglia liquidity is improving but remains lower at 12-24 months on secondary comune stock requiring longer sale timelines.
Get an Italy property shortlist
Tell us your budget and region (Tuscany, Lake Como, Puglia, Milan, Sardinia). We reply within one business day with options matched to your goals.