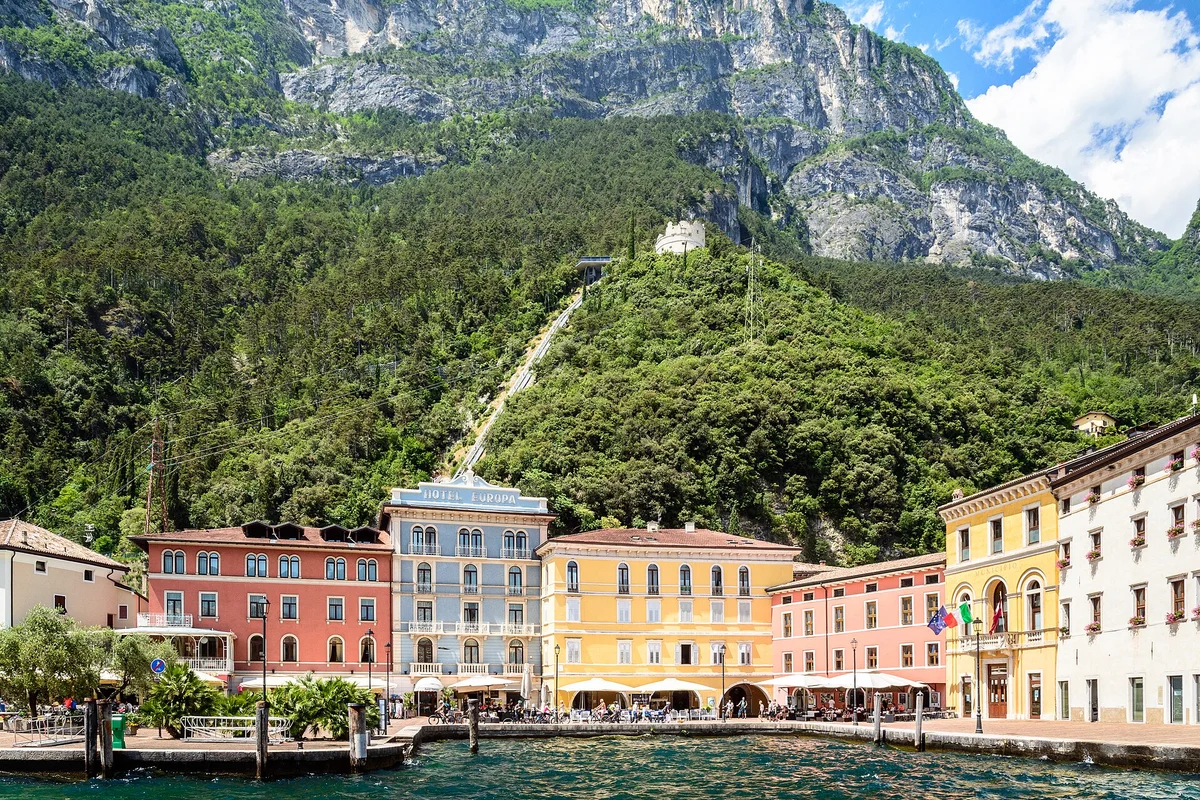
Lake Garda versus Lake Como is Italy’s most consequential lake property decision for high-net-worth buyers who already accept that northern Italian waterfront trades yield for lifestyle, scarcity, and euro-denominated store-of-value positioning. Both lakes sit within two hours of major economic hubs, both attract cross-border capital, and both compress rental returns relative to Puglia or Sicily. Yet they serve different mandates: Garda spreads across three regions with wider price tiers and deep German-Dutch holiday-home tradition; Como concentrates global villa prestige on a smaller, finite lakefront with Milan executive spillover.
This comparison maps prices, gross yields, short-term rental frameworks, buyer demographics, resale liquidity, and transport access so you can align lake with budget, hold period, and lifestyle utility. Neither market rewards yield-first investors. Both demand verified STR eligibility, realistic net-income models after cedolare secca, and patience on hillside stock that lacks frontage liquidity.
How do Lake Garda and Lake Como compare at a glance?
Lake Garda spans three regions with €2,800-9,000 per sqm waterfront and 2.5-4.5% gross yields while Como lakefront commands €8,000-25,000 per sqm with 2-3% yields and Milan train access in 40-50 minutes, shaping different HNW mandates on identical northern Italy lake allocation in Q2 2026.
Lake Garda trades at €2,800 to €9,000 per sqm across three shores while Como lakefront spans €8,000 to €25,000 per sqm in 2026. Gross yields run 2.5% to 4.5% on Garda against 2% to 3% on Como trophy frontage before 10% to 15% non-resident closing stacks.
STR rules vary by comune; German-Dutch buyers dominate Garda while Anglo-Swiss profiles cluster on Como. Track three closed sales in the same micro-district before anchoring offer price on either lake.
Lake desk (Q2 2026): Garda tickets €400,000-900,000 cluster 2.5-4.5% gross yields; Como frontage above €1.5M trades 2-3% with 12-18 month trophy resale cycles on Bellagio stock.
| Factor | Lake Garda | Lake Como |
|---|---|---|
| Geographic span | Lombardy, Veneto, Trentino (three regions) | Lombardy core, smaller lake |
| Prime waterfront €/m² | €4,500-9,000 (Sirmione, Riva, Salò) | €8,000-25,000 (Bellagio, Cernobbio) |
| Mid-tier €/m² | €2,800-5,500 (Bardolino, Lazise, Desenzano) | €4,000-8,000 (hillside lake-view) |
| Gross rental yield | 2.5-4.5% | 2-3% (lakefront); 2.5-3.5% hillside |
| Dominant foreign buyers | German, Dutch, Austrian, Swiss | American, British, Swiss, Gulf, Milan IT |
| Primary airport hub | Verona (25-45 min) | Milan Malpensa/Linate (50-75 min) |
| Financial centre link | Verona, Brescia; Milan 90-110 min west | Milan 40-50 min by train |
| STR regulatory heat | Moderate (varies by comune) | High (lakefront condo bans) |
| Trophy liquidity | Strong €300k-1.5M; thinner above €3M | Exceptional above €2M frontage |
| Primary buyer goal | Lake lifestyle + rental offset | Scarcity + preservation + Milan link |
Garda wins accessibility for central European buyers and broader price flexibility. Como wins irreplaceable frontage narrative and Milan-linked trophy demand. Your mandate determines which rows matter most.
- Garda spans three regions, which is why its supply is deeper and its pricing lower than Como’s.
- Dock and mooring rights on both lakes frequently sit outside the deed as state concessions.
- Concession remediation on dock-marketed stock commonly runs €15,000 to €40,000.
How Do Entry Prices Compare on Garda and Como?
Garda is consistently the lower entry of the two and the gap is structural. Como’s shoreline is short, steep and effectively fixed in supply, while Garda’s longer and more varied perimeter spans three regions, so foreign buyers there reach waterfront at a materially lower price per sqm.
Lake Como compresses investor attention into a narrower, higher band documented in the Lake Como property investment guide. Direct lakefront in Bellagio, Cernobbio, and Tremezzina trades €8,000-25,000/m². Como city and Menaggio lake-view stock sits €5,000-8,000/m². Hillside properties without frontage or dock access trade €4,000-8,000/m² but face 40-60% discounts to frontage on exit, a pricing cliff buyers often underestimate.
| Cost Category | Lake Garda (premium blend) | Lake Como (prime + hillside) |
|---|---|---|
| Waterfront €/m² | €4,500-9,000 | €8,000-25,000 |
| Mid-tier lake-view €/m² | €2,800-5,500 | €4,000-8,000 |
| Entry apartment (80 m²) | €224,000-440,000 (east shore); €360,000-720,000 (Sirmione) | €400,000-640,000 (Como quality); €800,000+ (prime village) |
| Entry villa (200 m²) | €600,000-1.8 million (west/east); €1-2.5M (Sirmione/Riva frontage) | €1.6-5 million+ (lakefront or prime view) |
| Renovation (historic) | €1,500-2,800/m² | €2,000-3,500/m² |
| Transaction costs | 10-15% | 10-15% |
| Annual holding (villa) | €8,000-22,000 | €12,000-35,000+ |
Financial accessibility favours Garda for HNW buyers deploying €400,000-1.5 million who want genuine lake exposure without Como trophy entry. Como at comparable architectural quality typically demands €1 million minimum for credible lake-view stock and €2 million plus for frontage that justifies global villa resale narratives. Municipality context for Como’s gateway market sits in the Como area guide and Bellagio area guide.
- Garda’s perimeter spans three regions, which is why waterfront supply there is deeper than Como’s.
- Budget an all-in 10% to 15% on a non-resident second home on either lake.
- Dock and mooring rights on both lakes are frequently state concessions outside the deed.
Which Lake Delivers Better Rental Yields?
Garda returns around 4.5% gross on well-bought stock against Como’s compressed trophy yields, largely because Garda’s larger shoreline and German-led family tourism sustain a longer season than Como’s shorter, higher-priced one. Have a commercialista take both lakes to a net figure after IMU, cedolare secca and vacancy, since they carry different concession and works exposure behind similar headline yields.
Como lakefront delivers 2-3% gross on prime stock. A €3.2 million Bellagio frontage villa (€16,000/m² for 200 m²) might generate €80,000-100,000 gross STR in strong seasons, translating to 2.5-3.1% before 26% cedolare secca on short-term income, 18-25% management fees, and €18,000-30,000 annual maintenance. Hillside Como apartments perform marginally better on percentage terms but remain preservation markets. For worked examples across Italian regions, consult the Italy rental yield guide.
| Performance Metric | Lake Garda | Lake Como |
|---|---|---|
| Gross yield (typical) | 2.5-4.5% | 2-3% (frontage); 2.5-3.5% (hillside) |
| Long-term rental yield | 2.5-3.5% | 2-3% |
| STR yield (permitted zones) | 3.5-4.5% (east shore); 3-4% (west) | 2-3% (frontage); 2.5-4% (Como city) |
| Peak occupancy (STR) | 60-75% (May-Sept); 35-50% shoulder | 55-70% (May-Sept); 35-50% shoulder |
| Net yield after tax and costs | Often 1.5-3% | Often 0.5-2% |
| Income predictability | Moderate (German-Dutch repeat demand) | Low-Moderate (luxury seasonal) |
Tax treatment is identical in principle: cedolare secca at 21% on qualifying long-term contracts for up to two properties, 26% on short-term income, plus IMU property tax and platform fees. The difference is starting yield, not tax code. Capital appreciation partially closes total-return gaps: Garda prime shores have recorded 2-3.5% annual appreciation over the past decade; Como lakefront trophy assets track 2-4% on finite frontage with hillside lagging at 1-3%.
- Both lakes run a genuine season of roughly 4 to 5 months against 12 months of standing costs.
- Short-let income is taxed at 21% on the first unit and 26% on the second.
- Model annual occupancy rather than peak nightly rate before comparing the two lakes.
Who Buys on Lake Garda Versus Lake Como?
Buyer composition is the clearest difference between the two lakes. Garda draws a broad mid-market with strong German and Austrian demand, while Como attracts a narrower international group buying trophy assets, which is why Como pricing holds better at the top of the market but transacts less frequently and takes longer to sell.
Lake Como draws a narrower, wealthier international cohort detailed across Lake Como vs Liguria property comparisons. American, British, Swiss, and Gulf-state purchasers dominate trophy transactions. Milan executives and Lombardy business owners treat Como as a 40-50 minute weekend base linked to Milano Centrale. Typical Como buyer: age 50-70, net worth €5-50 million plus, allocating €2-15 million, prioritising privacy, Belle Époque architecture, and waterfront scarcity over monthly cash flow on 10-20 year horizons.
| Buyer Factor | Lake Garda | Lake Como |
|---|---|---|
| Dominant nationalities | DE, NL, AT, CH, IT (Verona-Brescia) | US, UK, CH, IT (Milan), Gulf |
| Typical budget | €350,000-1.8 million | €1-10 million+ |
| Primary motivation | Family lake lifestyle + rental offset | Scarcity + privacy + Milan link |
| Rental income priority | Moderate (often offsets IMU) | Low (lifestyle offset only) |
| Hold horizon | 7-12 years | 10-20 years |
| Repeat buyer depth | Very high (DE/NL generational) | High at trophy tier only |
Success on Garda requires shore-specific underwriting: eastern Veneto for German-Dutch STR volume, western Lombardy for Milan-weekend spillover at lower tickets, northern Trentino for sports tourism and Austrian cross-border flows. Success on Como requires verifying waterfront concessions, dock rights, and condominium STR eligibility before compromesso, properties without direct lake access rarely match frontage liquidity on exit.
How Do STR Restrictions and Compliance Compare?
The useful comparison of Lake Garda versus Lake Como runs on net figures, after entry costs and annual carry are deducted. 50 bands after IMU, 21% cedolare secca, and realistic vacancy assumptions reviewed with commercialista before lease registration. Three OMI-quartiere closed sales should set the offer, not the portal average.
Short-term rental income requires valid CIN registration, municipal SCIA or SUAR paths where applicable, Alloggiati Web guest filing, and tourist tax remittance. Both lakes operate within Italy’s national framework, but municipal enforcement and condominium bylaws create distinct operational landscapes.
Lake Garda regulatory environment varies by comune and province. Sirmione enforces moderate oversight on historic peninsula zones with tourist tax collection and periodic inspections. Riva del Garda and Torbole maintain established tourism infrastructure supporting licensed STR with standard CIN/SCIA compliance. Bardolino, Lazise, and Desenzano generally permit STR on verified residential stock, though condominium bans exist in specific buildings. Eastern shore municipalities benefit from decades of German-Dutch holiday rental culture, creating clearer operational precedent than Como’s residential lakefront condominiums.
Lake Como constraints concentrate in building use on prime frontage. Como, Bellagio, Menaggio, and Lecco require SCIA classification. Prime lakefront condominiums often prohibit continuous short-term tourist activity regardless of municipal permissiveness. Waterfront paths and private docks may trigger concessione demaniale review. Hillside municipalities generally permit STR with standard compliance, but buyers targeting Bellagio nightly rates must verify bylaws before modelling income.
| STR Factor | Lake Garda | Lake Como |
|---|---|---|
| CIN requirement | Yes, all properties | Yes, all properties |
| Municipal licensing | SCIA; comune-specific caps | SCIA + zone restrictions |
| Condominium bans | Select buildings (check bylaws) | Common on prime lakefront |
| Tourist tax | €1-2.50/night (varies) | €1.50-2.50/night |
| Cedolare secca (STR, non-resident) | 26% | 26% |
| Enforcement intensity | Moderate (east shore lower friction) | Moderate-High (prime zones) |
Regulatory due diligence is non-negotiable on both lakes. Confirm STR eligibility in writing before compromesso, not after renovation. Buyers comparing Como against coastal alternatives should cross-read Lake Como vs Liguria property for parallel STR dynamics on the Riviera.
Which Lake Offers Better Resale Liquidity?
Garda exits faster at the mid-market. Its German and Dutch repeat-buyer pool absorbs €400,000-800,000 stock in months rather than seasons. Como’s liquidity concentrates at the top: trophy assets above €2,000,000 take 12-24 months, and mid-market lakefront competes against a much narrower audience.
- Track three OMI-quartiere closed sales in each city before pricing Lake Garda versus Lake Como exit tickets.
- Model time-on-market at 6-18 months depending on foreign enquiry depth at €300,000 reference bands.
- Confirm parking deeds and conformità documentation on portal listings before marketing to Anglo-American buyers.
Liquidity patterns bifurcate differently on each lake. Lake Garda benefits from deep repeat demand in the €300,000-1.5 million band where German and Dutch buyers transact regularly. Quality apartments in Bardolino, Lazise, and Malcesine sell within 12-24 months when priced within 5-8% of market. Sirmione peninsula stock above €1.5 million faces longer timelines (18-30 months) unless frontage and thermal-zone positioning justify premium asking. Ultra-trophy Garda villas above €3 million lack Como’s global auction depth, resale relies on Italian and DACH UHNW networks.
Como liquidity is exceptional at the trophy tier. Prime lakefront villas above €2 million in Bellagio and Cernobbio sell within 12-18 months to international buyers when marketed through cross-border agencies. Below €1.5 million, Como hillside stock without frontage stretches timelines to 18-30 months and may require 10-15% price adjustments. The buyer pool narrows but deepens at ultra-luxury: family offices and multi-property villa collectors compete for finite frontage.
Pricing stability during 2020-2022 favoured both lakes’ prime stock over secondary southern Italy. Garda eastern shore recovered strongly with German travel rebound. Como trophy frontage showed minimal decline before accelerating 2022-2025 on Milan financial sector growth. For exit planning, match asset tier to lake: Garda mid-tier offers broader replacement buyers; Como frontage offers fewer but wealthier bidders.
How do Milan and Verona access compare for Garda versus Como buyers?
Access shapes the buyer pool more than price does. Como sits 40-50 minutes from Milan Centrale, which is why its lakefront attracts Milanese executives. Western Garda leans on Verona Villafranca, 25-45 minutes from the eastern shores, which is why its repeat buyers are German and Dutch on €400,000-2,000,000 tickets.
Lake Como offers Milano Centrale in 40 to 50 minutes from Como San Giovanni on FNM regional trains; Lake Garda offers Verona Villafranca in 25 to 60 minutes across shore towns. Those links shape buyer nationality, visit frequency, and year-round versus peak-season rental demand patterns on each lake.
Lake Como’s decisive advantage is Milan proximity. Milan Malpensa Airport sits 60-75 minutes from Como; Linate 50-60 minutes. Milan’s financial, fashion, and corporate infrastructure creates year-round executive demand spillover. Many Como owners commute weekly during shoulder seasons while renting peak summer weeks.
Lake Garda’s hub is Verona, not Milan. Verona Villafranca Airport reaches Bardolino and Lazise in 25-35 minutes, Desenzano and Sirmione in 35-45 minutes, Riva del Garda in 50-60 minutes. Munich lies 3.5-4 hours via Brenner, making Garda the natural lake for German buyers who reject Como’s Milan orbit. Milan sits 90-110 minutes from western Garda by A4 motorway, usable for weekend access but not daily executive commuting. Brescia and Verona provide regional employment and services; Trento anchors northern shore buyers.
| Infrastructure Factor | Lake Garda | Lake Como |
|---|---|---|
| Nearest major airport | Verona (25-60 min by shore) | Milan Malpensa (60-75 min) |
| Train to Milan | 90-120 min (Desenzano-Peschiera line + connection) | 40-50 min (Como-Milano) |
| German highway access | Brenner/A22 to Riva (strong) | Via Switzerland or Milan ring |
| Primary lifestyle draw | Sailing, windsurf, family tourism | Villa culture, privacy, Milan link |
| Marina/boat culture | Strong (sailing, ferries) | Lake boating, private docks |
| Year-round livability | Moderate-High (east shore) | Moderate (seasonal peak) |
Lifestyle differs as much as infrastructure. Garda blends Mediterranean climate with Alpine scenery, olive groves on western shores, lemon groves near Limone, and active sports tourism. Como sells Belle Époque villa aesthetics, narrow lake geometry with dramatic Alpine walls, and global celebrity-adjacent branding. Garda suits active families and central European second-home tradition. Como suits ultra-HNW villa privacy and Milan-linked executive weekends.
- Como sits closer to Milan, which supports weekday as well as weekend use.
- Garda is served by both Verona and Milan, widening the German and Austrian drive-in catchment.
- Access shapes the letting calendar: a 4 to 5 month season behaves differently from year-round weekend demand.
When does Lake Garda suit the buyer better?
Garda suits foreign buyers who want waterfront exposure at a lower entry, a deeper resale pool and faster transactions, with well-bought stock returning around 4.5% gross. It suits them less well where the objective is trophy scarcity, because Garda’s shoreline is long enough that no single address is irreplaceable.
Lake Garda suits buyers with €350,000 to €1.8 million budgets who want German and Austrian resale depth without Lake Como trophy premiums. As of Q2 2026, 2.5% to 4.5% gross yield on furnished leases with 10% to 15% non-resident closing before compromesso wires.
- Budget sits in the €350,000-1.8 million band where quality lake stock exists without Como trophy premiums
- German, Dutch, or Austrian connectivity matters for personal use and resale buyer depth
- Rental income at 2.5-4.5% gross helps offset IMU, maintenance, and management on a 7-12 year hold
- Verona airport access (25-45 minutes) fits your travel pattern better than Milan-centric logistics
- Family lake lifestyle, sailing, and sports tourism drive the purchase more than villa trophy narrative
- You want three-regional optionality: Lombardy west, Veneto east, Trentino north at different price tiers
- STR operational friction tolerance is moderate, with Bardolino-Lazise offering clearer precedent than Como lakefront condos
Optimal Garda strategies: Bardolino or Lazise apartment for German-Dutch STR demand; Sirmione peninsula for premium thermal-adjacent frontage; Riva or Malcesine for northern sailing tourism. Request curated stock through our property shortlist service once municipality and STR eligibility are defined.
When does Lake Como suit the buyer better?
Como suits a buyer whose priority is the address and the Milan connection (40-50 minutes to Centrale) rather than the letting season. It also suits anyone above €2,000,000, where Garda has little comparable stock. Below €800,000, Garda usually offers more house and a longer season.
Lake Como fits capital-preservation buyers with €1.5 million plus budgets who accept 2% to 3% gross yields on finite lakefront scarcity. Screening (Q2 2026) shows Milan commuter demand supports 40 to 50 minute rail links with 21% cedolare secca on qualifying long leases after rogito.
- Capital preservation and finite lakefront scarcity outweigh rental yield in your mandate
- Budget exceeds €1.5 million for meaningful lake-view exposure, or €2 million plus for frontage
- Milan business corridor access (40-50 minutes by train) adds personal or corporate utility
- Multi-generational villa planning and global brand recognition (Bellagio, Cernobbio) drive the purchase
- You accept 2-3% gross yield and near-zero net income after tax on trophy stock
- Hold period exceeds 10 years to capture scarcity appreciation on irreplaceable frontage
- Anglo-Saxon, Swiss, or Gulf buyer profile aligns with established Como resale networks
Optimal Como strategies: direct lakefront with existing concessione demaniale and verified STR rights; Como city apartment for Milan-linked buyers; Bellagio villa for ultra-HNW preservation. Deep market mechanics live in the Lake Como property investment guide with municipality detail in Como and Bellagio.
Which decision framework fits Lake Garda versus Lake Como?
Three answers settle the choice before either lake is priced: the intended use, the realistic holding period, and whether liquidity or scarcity matters more. Buyers who resolve those first rarely find the €/sqm comparison decisive, because the two lakes are selling different things at similar-looking numbers.
Buyers in 2026 match €650,000 Garda tickets at €6,000 to €7,500 per sqm against €3 million Como villas before 10% to 15% closing stacks, budget, hold period, and income target must align with each lake’s yield and liquidity profile.
- €650k German HNW family: Garda Bardolino or Lazise at €6,000 to €7,500 per sqm for 3.5% to 4.5% gross STR.
- €3m Milan executive: Como trophy villa with Milan spillover and preservation-led resale depth.
- Yield-first under €500k: eastern Garda shore stock before Como hillside without frontage.
- US second-home buyer: compare STR compliance costs by comune before caparra on either lake.
As of Q2 2026, 9% second-home registration tax, 21% cedolare secca on qualifying leases, and 5-year hold before compromesso deposit wires.
Scenario 1: German HNW family, €650,000, holiday home plus rental offset
Choose Lake Garda. A Bardolino or Lazise apartment at €6,000-7,500/m² generates 3.5-4.5% gross STR with established German-Dutch demand. Brenner corridor access supports personal use. Como at €650,000 buys hillside without frontage, yielding under 3% with weaker resale depth for this budget.
Scenario 2: Milan executive, €3 million, weekend villa plus preservation
Choose Lake Como. Direct lake access, 45-minute train to Milano Centrale, and Bellagio or Cernobbio frontage match the lifestyle and preservation brief. Garda cannot replicate Como’s global villa narrative at this tier.
Scenario 3: Dutch couple, €480,000, 10-year hold with IMU offset
Choose Lake Garda. Eastern shore stock with verified STR eligibility delivers income that Como hillside cannot match at this ticket. Repeat Dutch buyer pool supports exit in year 8-10.
Scenario 4: American UHNW, €8 million, trophy estate
Choose Lake Como. Finite frontage, celebrity-adjacent market positioning, and 12-18 month trophy liquidity above €2 million outperform Garda’s thinner ultra-luxury auction depth.
Scenario 5: Portfolio builder adding northern Italian lake exposure
Hold Garda for income-capable stock (€500,000-1.2 million east shore) and add Como lake-view for scarcity diversification. Do not force one lake to deliver both yield and trophy preservation.
What are the pros and cons of Lake Garda versus Lake Como?
Como offers scarcity and global recognition at the cost of a narrow, price-sensitive resale market and lakefront rights that frequently sit outside the deed. Garda offers a deeper mid-market with German-led family tourism, a longer season and around 4.5% gross, without any single address carrying an irreplaceable name.
Como offers foreign buyers scarcity, international recognition and a thinner, more price-sensitive resale market. Garda offers a deeper mid-market with stronger German and Austrian demand and faster transactions, at the cost of the trophy status that supports Como pricing through a downturn.
Lake Garda versus Lake Como comparisons should model identical €400,000-650,000 lakefront tickets, German tourist enquiry share, and 3-4% gross furnished yields before choosing Veneto value against Lombardy ultra-prime pricing.
- Broader price tiers from €2,800/m² east shore to €9,000/m² Sirmione frontage
- Slightly higher yields (2.5-4.5%) on mid-tier stock
- Deep German-Dutch-Austrian buyer pool supporting €300k-1.5M liquidity
- Verona airport proximity and Brenner Munich access
- Three-regional micro-market optionality within one lake
- Strong sailing and active tourism supporting shoulder-season occupancy
Lake Garda challenges:
- Lower global trophy brand than Como for ultra-luxury exit above €3M
- Three-province regulatory variance requires comune-specific DD
- Milan access 90-110 minutes from west shore limits executive commuting
- Premium peninsula stock (Sirmione) faces thermal-zone building constraints
- Eastern STR success depends on condominium bylaws per building
- Hillside stock without lake access discounts similar to Como on resale
Lake Como advantages:
- Finite lakefront scarcity at €8,000-25,000/m² supporting long-term appreciation
- Global villa prestige and exceptional trophy liquidity (12-18 months above €2M)
- Milan train 40-50 minutes creating executive weekend demand
- Deepest ultra-HNW buyer pool for frontage above €2 million
- Established English-speaking architect and management infrastructure
- Stronger capital preservation narrative on prime Bellagio and Cernobbio frontage
Lake Como challenges:
- Lowest yields in Italian lake markets (2-3% gross frontage)
- Extreme entry pricing (€1.5-3M meaningful villas standard)
- Lakefront condominium STR bans common in prime zones
- Waterfront concession and dock permitting complexity
- Hillside stock below €1.5M lacks trophy resale characteristics
- Seasonal demand concentration May-September on rental income
Insider tip: Model both lakes with identical capital, hold period, and tax assumptions before choosing. Per sqm gaps often reverse after IMU, 26% STR cedolare, 20% management, and vacancy on hillside stock that agents marketed as lakefront-adjacent.
| Lake Garda | Lake Como | |
|---|---|---|
| Entry per sqm | Lower | Higher, scarcity-driven |
| Resale pool | Broad mid-market | Narrow, international |
| Season | Roughly 4-5 months | Roughly 4-5 months |
| IMU, second home | 0.86%-1.06% | 0.86%-1.06% |
What is the regional verdict for Lake Garda versus Lake Como?
Como is the scarcity position and Garda the liquidity position. For foreign buyers that means Como rewards patience and a long hold, while Garda rewards those who may need to sell inside 5 years and want a deeper pool of buyers waiting when they do.
Lake Garda versus Lake Como in 2026 spans €2,800 to €9,000 per sqm on Garda against €8,000 to €25,000 per sqm on Como lakefront before 10% to 15% non-resident closing stacks. Neither lake suits yield-first investors prioritizing 6% gross spreads over trophy scarcity.
Both reward HNW capital that values Italian northern lake identity with realistic net income, liquidity timelines, and regulatory care.
- Garda fit: accessible tickets, Verona hub access, and income up to 4% gross on verified eastern shore stock with German-Dutch buyer depth.
- Como fit: Milan spillover, global villa branding, and finite frontage supply for preservation buyers who accept 2% to 3% gross yields.
- Underwriting rule: model 21% cedolare secca, IMU, and STR compliance by comune before compromesso on either lake.
For curated opportunities on either lake after municipality and STR screening, use our property shortlist service. For Como depth, start with the Lake Como property investment guide. For yield benchmarking nationally, see the Italy rental yield guide.
What field data does Italian Estate track on Lake Garda versus Como?
Lake field data here refers to Garda prime waterfront at €4,500-9,000 per sqm delivering 2.5-4.5% gross yields against Como frontage at €8,000-25,000 per sqm compressing toward 2-3% before IMU and condominium STR bans on Bellagio residential blocks, per Screening notes for 2026.
Lake field data here refers to Garda prime waterfront at €4,500-9,000 per sqm delivering 2.5-4.5% gross yields against Como frontage at €8,000-25,000 per sqm compressing toward 2-3% before IMU and condominium STR bans on Bellagio residential blocks.
- Italian Estate screening tracks enquiry share, per sqm bands, and gross yield spreads on Lake Garda versus Lake Como.
- Foreign buyer share on prime rogiti is benchmarked against Gate-away and Abitare aggregates for Q2 2026.
- Modeled non-resident closing stacks run €4,500 on second-home purchases before wire authorization.
Lake Garda property suits buyers seeking Milan or Verona commuter access with 25% to 40% lower per sqm than Como equivalents on comparable lake-view stock. STR licensing requires national CIN plus municipal density rules; Garda comunes enforce seasonal caps on Desenzano and Riva del Garda waterfront. Como geotechnical surveys and Soprintendenza filings mandatory on Belle Époque villa stock before exterior capex. IMU on €800,000 Como ticket often runs 4,200 to €6,500 annually; Garda €450,000 ticket IMU 1,800 to €3,200. Winter STR occupancy Nov-Feb can fall below 35% on both lakes; underwrite shoulder seasons and Milan long-term fallback rather than July-only pro formas. Hold seven to ten years on trophy Como stock for HNW liquidity. Modeled non-resident closing stack runs 10% to 12% on second-home purchases with 5-year minimum hold benchmarks on Italian Estate 2026 files.
What Structurally Separates These Two Lakes?
Buyer composition is what actually separates the two lakes, and it is more decisive than any price-per-sqm table. Foreign buyers on Como are usually competing for scarce lakefront in a narrow, trophy-led market, while Garda’s larger and more varied shoreline supports a deeper mid-market that trades more often.
| Dimension | Lake Como | Lake Garda |
|---|---|---|
| Shoreline supply | Narrow, steep, scarce | Longer and more varied |
| Buyer pool | Trophy-led, international | Broader mid-market, strong German and Austrian demand |
| Resale liquidity | Thinner at the top, price-sensitive | Deeper, transacts more frequently |
| Lakefront rights | Frequently a state concession | Same issue, but less often the price driver |
- On both lakes, dock and mooring rights commonly sit outside the deed; concession gaps cost €15,000 to €40,000 to remediate.
- Model annual occupancy rather than peak-week rates: the genuine season runs roughly 4 to 5 months.
- IMU on a second home is 0.86% to 1.06% of cadastral value on either lake, set by the comune.
Frequently Asked Questions
Lake Garda offers materially lower entry across almost every tier. Prime Garda waterfront in Sirmione or Riva del Garda trades €4,500-9,000/m², while eastern shore towns like Bardolino and Lazise sit €2,800-5,500/m². Lake Como lakefront commands €8,000-25,000/m² with meaningful villas starting €1.5-3 million. Garda suits HNW buyers who want lake lifestyle below Como trophy pricing.
Lake Garda typically delivers 2.5-4.5% gross on mid-tier apartments and villas, slightly above Como's 2-3% lakefront band. Garda's broader price spectrum and stronger German-Dutch holiday demand support income math on €400,000-900,000 stock. Como compresses yields because purchase premiums embed global villa scarcity upfront. Both remain capital-preservation markets, not yield-first plays.
Both lakes require national CIN registration and municipal SCIA compliance. Como lakefront condominiums in Bellagio and Cernobbio often ban continuous tourist use in building bylaws. Garda comuni vary: Sirmione and Riva enforce moderate caps, while Bardolino, Lazise, and Desenzano maintain more permissive frameworks for licensed STR. Verify eligibility before offer on both lakes.
Lake Garda historically dominates German and Dutch second-home demand through Brenner corridor access, campsite culture, and sailing tourism. Towns like Bardolino, Lazise, Malcesine, and Riva see repeat cross-border buyers. Lake Como draws Anglo-Saxon, Swiss, and Gulf HNW capital seeking ultra-luxury villa privacy and Milan executive links rather than family holiday volume.
Lake Como wins decisively on Milan access. Como city connects to Milano Centrale in 40-50 minutes by train, with Malpensa airport 60-75 minutes away. Western Lake Garda (Desenzano, Sirmione) sits 90-110 minutes from Milan by road. Garda's stronger hub is Verona Villafranca airport at 25-45 minutes to eastern and southern shores.
Como maintains exceptional liquidity for trophy lakefront above €2 million through global villa branding, prime Bellagio and Cernobbio stock sells within 12-18 months when priced correctly. Garda offers broader liquidity across €300,000-1.5 million bands thanks to German-Dutch buyer depth, but ultra-trophy Garda frontage lacks Como's international auction narrative.
Como lakefront wins pure scarcity preservation on finite frontage, Milan wealth spillover, and decades of celebrity-adjacent branding. Garda wins balanced HNW allocation when budget sits €500,000-2 million, Verona-Munich connectivity matters, and slightly better yield headroom helps offset holding costs. Many portfolios hold Garda income-capable stock plus Como lake-view for prestige diversification.
Get an Italy property shortlist
Tell us your budget and region (Tuscany, Lake Como, Puglia, Milan, Sardinia). We reply within one business day with options matched to your goals.