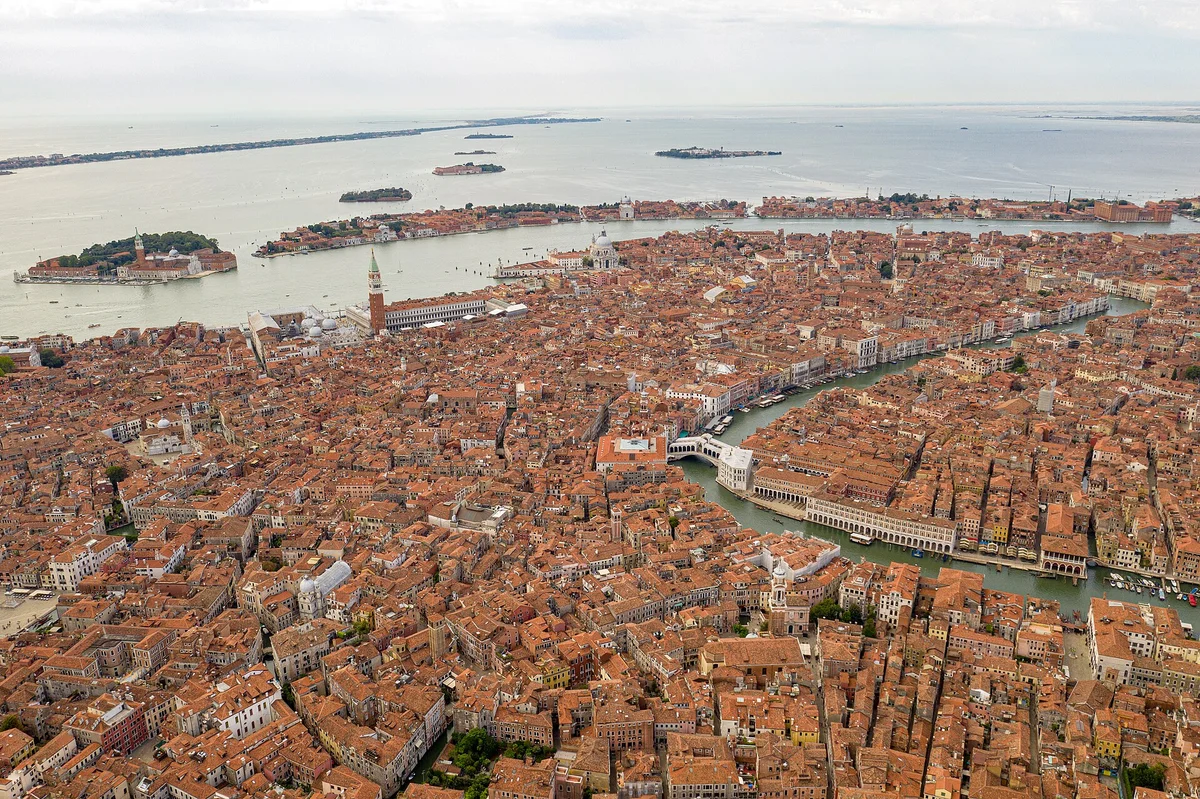
Quick answer: Venice historic center trades at €3,800-5,600/m² in prime sestieri with gross yields of 2.0-4.5% depending on rental track and licensing status. UNESCO heritage rules, lagoon logistics, and Italy’s national CIN requirement sit beneath Venice’s unique two-track STR system: 120 tourist days on the basic track or year-round rental only on the premium track with SCIA and in-person check-in. Mestre mainland at €1,800-2,700/m² offers better residential yield and lower flood risk. Acqua alta insurance and conformità due diligence are non-negotiable before you commit capital.
Venice is not a standard Italian city investment. The lagoon geography, UNESCO listing, depopulation of the historic center below 48,000 residents, and Italy’s most debated short-term rental framework create a market where headline prices and regulatory status matter more than generic national averages. Foreign capital still flows here for euro-zone trophy assets and tourism-linked income, but success requires separating mainland Mestre underwriting from sestiere-level compliance on the islands. Cross-read our Rome property investment guide for capital-city heritage parallels and our Tuscany property investment guide for regional yield comparison before you anchor on Venice alone.
What is the Venice property market doing in 2025-2026?
Venice divides into a lagoon market where nothing new can be built and a mainland market at Mestre where ordinary supply exists, and the two behave nothing alike. San Marco trades at €4,200-5,600 per sqm against Mestre Centro at €1,825-2,675, and yields invert accordingly.
Model 9% registration tax on a second home, 21% cedolare secca on a qualifying lease, a 10-15% non-resident closing stack, and 90-day execution windows where visa or rogito timelines apply.
| Market indicator | 2025-2026 estimate | What investors should read from it |
|---|---|---|
| Venice municipality average (asking) | €2,459/m² (city-wide OMI blend) | Masks San Marco premium vs Marghera discount |
| San Marco / prime sestieri | €3,800-5,600/m² | Trophy pricing, strictest STR scrutiny |
| Cannaregio / Castello / Dorsoduro | €3,875-4,850/m² | Strong foreign recognition, canal premiums |
| Mestre Centro | €1,825-2,675/m² | Mainland value, rail link to Santa Lucia |
| Marghera / peripheral mainland | €1,150-1,310/m² | Yield focus, weaker foreign resale brand |
| Mestre OMI growth YoY | +4.95% to €2,094/m² (2026) | Mainland catching up, not speculative spike |
| Historic center population | Under 48,000 residents | Housing pressure drives political STR debate |
| Median apartment ticket (city-wide) | ~€370,000 | Two-bedroom lagoon units often exceed this |
| Transaction cost load | 8-12% second home | Same national framework as Rome and Tuscany |
| New build supply in lagoon | Effectively zero | Price support from scarcity, not construction |
Venice behaves differently from Milan’s corporate rental base or Puglia’s yield-first coastal towns. Scarcity of legal residential conversions in the lagoon supports prices, but the same constraint caps STR expansion and pushes political risk to the top of any underwriting model.
- Verify visura catastale and conformità before caparra.
- Budget 28 to 32 days for complete Nulla Osta dossiers when applicable.
| Venice tax checkpoint | 2026 typical |
|---|---|
| Second home registration | 9% cadastral |
| STR licensing (CIN) | Mandatory |
| Flood-zone insurance | Budget annually |
How do UNESCO constraints affect Venice property buyers?
For property investors, UNESCO overlay means three practical constraints. First, new housing in the lagoon is effectively blocked, so price support comes from stock conversion and renovation, not greenfield supply. Second, renovation timelines run 4-12 months longer than mainland Italy when heritage approval is required, with cost premiums of 25-45% documented in our heritage restricted property Italy guide. Third, use changes from pure residential to tourist accommodation face municipal caps independent of UNESCO, but heritage status makes physical expansion to add bedrooms or terraces nearly impossible without specialist consent.
| UNESCO / heritage factor | Typical investor impact | Due diligence action |
|---|---|---|
| Soprintendenza vincolo | External works need prior authorization | Order certificato di vincolo before compromesso |
| PRG historic center zoning | Height, volume, and density frozen | Review comune piano regolatore with geometra |
| Landscape constraint (lagoon views) | Roof terraces and altane restricted | Survey existing altana legal status |
| Unauthorized past works | Inherited liability, enforcement persists | Commission conformità urbanistica review |
| Material and color rules | Approved finishes only on facades | Get heritage-experienced contractor quotes |
Venice is not Florence, where a 2025 municipal ban on new STR authorizations in the UNESCO centro storico made global headlines. Venice holds unique national powers under the 2022 Pellicani amendment to regulate tourist rentals directly. Heritage and STR policy stack rather than replace each other. A canal-front apartment can be legally owned yet impossible to expand or convert without years of permits.
Citability block: research on Venice vincolati purchases (Q2 2026): a foreign buyer targeting a Cannaregio second-floor apartment at €420,000 should budget €18,000-€32,000 for pre-purchase technical due diligence including geometra survey, conformità urbanistica, certificato di vincolo request, and APE verification. Soprintendenza approval for facade restoration on the same unit typically adds 6-9 months and 30-40% to contractor quotes versus a comparable Mestre refurb. Buyers who skip heritage search before compromesso inherit abusi edilizi liability and can face stop-work orders after closing. Treat UNESCO friction as a line-item capex and timeline input, not a footnote.
- Verify visura catastale and conformità before caparra.
What is Venice’s short-term rental licensing crisis?
Since the Giunta Comunale resolution of 24 October 2024, the historic center operates a two-track optional regulation for affitti brevi. Track one allows up to 120 tourist rental days per year without joining the municipal premium registry, but requires advance communication to the comune of exact rental dates. Track two allows year-round tourist use for owners who filed SCIA, enrolled in the municipal registry, provide in-person guest check-in, and meet additional service standards. Keybox locks on public-facing structures are prohibited in the historic center.
The premium track initially allowed enrollment only within 120 days of the regulation taking effect, with the experimental phase running until 31 December 2026. That closure created a licensing crisis for buyers who acquired in 2026 expecting to open new year-round STR operations on the premium pathway. Council attempts at a two-year moratorium on new authorizations failed procedurally in early 2026, leaving policy unstable but compliance mandatory on existing tracks. Full national context sits in our short-term rental rules Italy and Italy holiday let licensing guides.
| STR element | Basic track (120 days) | Premium track (year-round) |
|---|---|---|
| Municipal registry | Not required | Mandatory enrollment |
| SCIA touristica | Not required for basic track | Required |
| Guest check-in | Standard national rules | In-person check-in required |
| Day declarations | Advance comune notification | Registry-linked reporting |
| CIN / CIR | Mandatory nationally | Mandatory nationally |
| Geographic scope | Historic center + islands per regulation | Historic center focus |
| Policy horizon | Subject to 2026 review | Premium enrollment window closed to new entrants |
Operators on Murano, Burano, Lido, and mainland Mestre fall outside the October 2024 historic-center regulation but still need national CIN and Veneto CIR. Do not assume a Cannaregio compliance template applies to a Mestre apartment without verifying comune jurisdiction.
Investors should treat STR revenue in Venice as license-dependent, not location-dependent. A listing marketed as “Airbnb-ready” without traceable premium registry status or verified remaining day allocation on the basic track can destroy pro forma returns. Trace CIN, CIR, municipal registry entries, and SCIA filings against the exact cadastral sub-unit before paying a tourist-rental premium on acquisition price.
-
Verify visura catastale and conformità before caparra.
-
A CIN registration is required before any unit is advertised for tourist use.
-
The comune monitors and caps tourist letting more tightly than most Italian cities.
-
Short-let income is taxed at 21% on the first unit and 26% on the second.
Mestre versus historic center: where should investors buy?
Historic center sestieri (San Marco, San Polo, Dorsoduro, Cannaregio, Castello, Santa Croce) command global brand recognition. Two-bedroom renovated apartments commonly list €450,000-850,000 depending on canal exposure, floor level, and elevator access. Foreign resale liquidity is highest here. Costs include higher acqua alta exposure on ground floors, strict STR rules, expensive condominio spese, and renovation access via canal logistics.
Mestre Centro offers mainland living 10-20 minutes from Piazzale Roma by bus or train. Pricing at €1,825-2,675/m² per OMI zones delivers 40-60% discounts versus San Marco on a per-metre basis. Long-term rental demand from hospital workers, university staff, and Venice commuters supports gross yields of 4.0-5.5% on well-located stock. STR regulation follows Veneto and national rules without the historic-center two-track system. Foreign trophy buyers are rarer, so exit timing may depend more on local demand.
| Zone | Typical price €/m² | Gross yield band | STR framework | Best-fit buyer |
|---|---|---|---|---|
| San Marco | €3,800-5,600 | 2.0-3.5% | Historic two-track | Trophy / licensed STR |
| Cannaregio / Castello | €3,875-4,850 | 2.5-4.0% | Historic two-track | Lifestyle + regulated STR |
| Dorsoduro / San Polo | €3,975-4,850 | 2.5-4.0% | Historic two-track | Cultural tourism base |
| Giudecca | €3,500-4,500 | 2.5-3.8% | Island, separate access | Quiet lagoon lifestyle |
| Lido | €2,700-3,600 | 3.0-4.5% | Beach seasonality | Seasonal STR |
| Murano / Burano | €2,400-2,800 | 3.0-4.5% | National CIN only | Niche tourism |
| Mestre Centro | €1,825-2,675 | 4.0-5.5% | National + Veneto | Residential yield |
| Marghera | €1,150-1,310 | 4.5-6.0% | National + Veneto | Value / local tenant |
Insider tip from our Venice file review: agents often market “Venice” stock that cadastrally sits in Mestre or Marghera. Verify the exact address, sestiere, and vaporetto versus bus access before paying a lagoon premium. A mainland unit can be a smart investment without being a historic center asset.
- Verify visura catastale and conformità before caparra.
How does lagoon access change ownership costs and renovation timelines?
Renovation logistics intensify cost and delay. Building materials arrive by barge with canal-side unloading windows subject to tide schedules and municipal traffic rules. Contractors charge premiums for hand-carrying fixtures up staircases in buildings without elevators. Palazzo units above the third floor without lift access trade at discounts that partial renovation cannot always recover.
| Lagoon access factor | Typical cost or delay | Investor implication |
|---|---|---|
| ACTV vaporetto pass (resident) | €600-900/year | Add to holding cost model |
| Water taxi (single trip) | €80-150 | STR guest transfer or emergency access |
| Barge delivery permit | €500-2,000 per project | Renovation quote variance |
| Elevator absence above 2nd floor | 10-25% price discount | Foreign buyer resistance on exit |
| Condominio spese (canal front) | €300-800/month | Erodes net yield fast |
| Waste collection (centro) | Specialized boat service | Operating cost for STR turnovers |
Lagoon access is not a lifestyle detail alone. It determines contractor availability, insurance assessments for delivery damage, and whether an STR operator can meet premium-track in-person check-in obligations without hiring local staff.
- Verify visura catastale and conformità before caparra.
What rental yields can Venice property investors expect?
Venice yields split by island and by letting track. Long residential lets return 2.0-3.5% gross in the historic centre against 4.0-5.5% in Mestre; the basic short-let track, capped at 120 days, reaches 3.0-4.0%; the premium 365-day track reaches 3.5-4.5% but requires an existing registry enrolment that cannot always be transferred.
| Strategy | Historic center gross | Mestre gross | Net after typical costs |
|---|---|---|---|
| Long-term residential | 2.0-3.5% | 4.0-5.5% | Often 1.5-3.0% |
| STR basic track (120 days) | 3.0-4.0% | 3.5-5.0% | Seasonality caps revenue |
| STR premium track (365 days) | 3.5-4.5% | N/A in same framework | Requires existing enrollment |
| Furnished medium-term | 2.8-4.0% | 3.8-5.0% | University and hospital demand |
National yield math and tax channels are covered in our Italy rental yield guide. Venice-specific underwriting should stress-test 120-day caps on the basic STR track and verify whether premium registry transfer is even possible on resale of a licensed unit. Yields modelled on full-year platform occupancy without proof of licence are the single most common pro forma error on Venice stock.
Citability block: Italian Estate yield scenario (Cannaregio two-bedroom, €520,000 purchase, 2026): gross STR revenue on the basic 120-day track at €180/night and 75% occupancy within the day cap produces roughly €16,200 annual gross, or 3.1% gross yield before IMU (€3,200), condominio spese (€4,800), management at 20% (€3,240), and cedolare secca at 21% (€3,400). Net cash flow approaches breakeven. The same unit on a verified premium track at 280 nights and €195/night can reach 4.1% gross, but only if SCIA, CIN, CIR, and municipal registry chain match the buyer at closing. Always reconcile license status with price.
- Verify visura catastale and conformità before caparra.
Who is buying Venice property: foreign buyer profiles in 2026?
Seven buyer groups make up Venetian foreign demand and they sort by budget and sestiere. Americans lead at €400,000-1.5M in San Marco, Dorsoduro and Cannaregio; British buyers follow at €350,000-900,000 in Cannaregio and Castello; German, Austrian and French buyers sit below them; and EU remote workers enter at €220,000-450,000 in Mestre and the Lido.
| Buyer origin | Typical budget | Preferred zones | Primary motivation |
|---|---|---|---|
| United States | €400k-1.5M | San Marco, Dorsoduro, Cannaregio | Euro asset, lagoon lifestyle |
| United Kingdom | €350k-900k | Cannaregio, Castello | Post-Brexit second base |
| Germany / Austria | €300k-700k | Giudecca, Mestre | Cultural access, some yield |
| France | €280k-650k | San Polo, Dorsoduro | Art and biennale linkage |
| Australia / Canada | €450k-1.2M | Canal-premium sestieri | Long-haul second home |
| EU remote workers | €220k-450k | Mestre, Lido | Long-term rent, lower ticket |
| Italian diaspora | €250k-600k | Family-linked sestieri | Emotional purchase |
Americans and British buyers purchase freely when reciprocity is satisfied. UK nationals face Schengen stay limits without EU residency. Full ownership rules are in our buy property Italy foreigner guide. Venice differs from Rome’s diplomatic and corporate tenant base covered in our Rome property investment guide and from Tuscany’s agriturismo yield play in the Tuscany property investment guide.
Foreign buyers overpay most often for STR potential without license verification and for ground-floor romantic canal views without flood insurance quotes.
- Verify visura catastale and conformità before caparra.
How does acqua alta affect insurance and ground-floor risk?
Property investors must separate three risk layers. Structural risk affects ground-floor and sub-ground units where moisture ingress damages floors, electrics, and furnishings. Insurance risk arises because standard polizza casa policies often exclude flood and acqua alta damage unless a specific alluvione rider is added. Operational risk hits STR operators who must cancel bookings, replace damaged goods, and manage guest safety during sirens.
| Acqua alta factor | Ground floor impact | Buyer action |
|---|---|---|
| MOSE closure events | Reduces extreme flooding | Confirm barrier operational history |
| 110 cm+ tide alerts | Pedestrian walkways, shop closures | Model STR cancellation days |
| Standard home policy | Often excludes flood | Request polizza alluvione quote |
| Electrical installations | Must meet raised thresholds | Survey post-flood remediation records |
| Furniture / STR inventory | Total loss risk on ground floor | Price discount or avoid ground floor |
Elevated acqua alta insurance premiums and deductibles can add €800-2,500 annually on vulnerable units. A San Marco ground-floor canal apartment priced 15% below comparable upper floors may still be uneconomic after insurance and lost rental nights. Mestre mainland stock carries materially lower flood exposure, another reason yield-focused buyers pivot terraferma.
- Verify visura catastale and conformità before caparra.
What due diligence steps protect Venice buyers?
Venice due diligence requires 3 water-specific checks beyond the standard Italian file, and none of them appears in an ordinary survey. A foreign buyer needs the ground-floor flood history for that exact address, the acqua alta protection actually installed, and evidence that foundations and salt-exposed elements were inspected rather than assumed, on top of the usual 10% to 15% closing stack.
| Check | Why it matters in Venice | Professional |
|---|---|---|
| Conformità urbanistica | Abusi edilizi common in old palazzi | Geometra |
| Certificato di vincolo | UNESCO / Soprintendenza constraints | Soprintendenza request |
| STR registry trace | Revenue model validity | Commercialista + comune |
| CIN / CIR verification | National legality | BDSR / Ross1000 lookup |
| Acqua alta / flood policy | Ground-floor viability | Insurance broker |
| Condominio minutes | STR bans, MOSE of spese spikes | Avvocato review |
| APE energy certificate | Legal requirement at sale | Seller provision |
| Altana / terrace status | Often unauthorized | Geometra survey |
Independent avvocato counsel through rogito is essential. Never rely solely on seller-recommended geometra for abusi checks. Heritage detail is expanded in heritage restricted property Italy.
- Verify visura catastale and conformità before caparra.
| Check | Why Venice differs |
|---|---|
| Ground-floor flood history | Acqua alta exposure varies street by street |
| Protection installed | Barriers and pumps are a capital item, not a fitting |
| Foundation survey | Salt and tide exposure shorten every maintenance cycle |
| Works access | Delivery by boat prices each job above mainland equivalents |
- Ground-floor flood history varies street by street, so ask for the specific address rather than the sestiere.
- Acqua alta barriers and pumps are capital items running into thousands, not fittings.
- Budget an all-in 10% to 15% on a non-resident second home before any of this.
What are the main costs of buying and holding Venice property?
Venice costs divide into the ordinary Italian stack and a set of charges unique to the lagoon. Alongside 9% registration on cadastral value and annual IMU, a buyer meets acqua alta protection, boat-based works logistics and salt exposure that shorten maintenance cycles on every element of the building.
Transaction load commonly reaches 8-12% above purchase price before renovation.
| Cost | Venice position |
|---|---|
| Registration, second home | 9% of cadastral value from a private seller |
| Annual IMU | 0.86% to 1.06% of cadastral value |
| Works logistics | Delivered by boat, which prices every job higher |
| Acqua alta protection | Barriers and pumps on ground floors |
| Maintenance cycle | Shortened by salt exposure and humidity |
What are the pros and cons of Venice property investment in 2026?
In favour: lagoon scarcity that no planning decision can reverse, and a mainland alternative at Mestre trading €1,825-2,675 per sqm with 4.0-5.5% gross on long leases. Against: short-let rules that frequently hold historic-centre net yields below 3.5%, and San Marco pricing at €4,200-5,600 per sqm that leaves no room for operational error. The two halves of this market suit opposite mandates.
| Advantages | Disadvantages |
|---|---|
| Unmatched global brand for resale narrative | Historic center net yields often under 3% |
| Scarcity supports lagoon pricing | STR policy instability through 2026 |
| MOSE reduces worst acqua alta events | Ground-floor flood and insurance risk |
| Mestre offers mainland yield alternative | Lagoon renovation logistics premium |
| Euro hard asset in iconic market | Depopulation drives political regulation |
| Strong foreign enquiry pool | Premium STR enrollment window largely closed |
| Murano / Lido niche tourism options | Condominio resistance to STR operators |
| National foreign ownership framework clear | License-dependent revenue models |
- red flag: verify premium STR registry survives rogito before paying tourist-income premiums.
- Budget 10% to 15% non-resident closing stacks on second-home rogiti in 2026 models.
How does Venice compare within the Italy investment map?
Venice is structurally unlike every other Italian market, because its constraints are physical as well as regulatory. A fixed building stock, restoration logistics delivered by boat and acqua alta exposure mean the maintenance burden is materially higher than any mainland city at a comparable price per sqm, before the 10% to 15% entry stack.
For cross-region tables and foreign buyer volumes, start with the national Italy property investment guide. For net yield math, use the Italy rental yield guide.
| Factor | Venice position |
|---|---|
| Maintenance burden | Structurally higher; acqua alta and salt exposure |
| Works logistics | By boat, which lengthens and prices every job |
| Letting regulation | CIN plus comune rules plus the regolamento |
| IMU, second home | 0.86% to 1.06% of cadastral value |
Closing checklist before you sign in Venice
The Venice checklist adds water to the standard Italian file, and every item on it is obtainable before the caparra. A buyer needs the ground-floor flood history, the protection installed, the foundation survey, and the ordinary conformità and condominium checks that apply anywhere in Italy.
- Confirm cadastral address: historic sestiere, island, or Mestre mainland.
- Obtain conformità urbanistica and abusi edilizi opinion from independent geometra.
- Request certificato di vincolo if facade or structural work is planned.
- Trace STR status: basic 120-day track, premium registry, or residential only.
- Verify CIN and Veneto CIR against exact sub-unit, not building-level marketing.
- Quote polizza alluvione for ground floor and near-ground units.
- Model net yield with IMU, spese, management, and 21-26% cedolare secca.
- Review condominio minutes for STR restrictions and major MOSE-related works assessments.
- Budget lagoon renovation logistics if buying unrenovated palazzo stock.
- Confirm independent avvocato engagement through rogito, not only pre-compromesso review.
Keep independent avvocato through rogito, not only pre-compromesso review.
Venice rewards buyers who treat UNESCO constraints, STR licensing, and acqua alta insurance as core underwriting inputs. Lagoon trophy assets can preserve capital. Mestre can deliver income. Confusing the two markets is the fastest path to disappointed returns.
Need Venice property research tailored to your budget?
If you are comparing Cannaregio, Dorsoduro, and Mestre opportunities, or need help tracing STR registry status on a historic center listing, our team publishes independent market research and connects you with licensed Italian partners. Get your personalized Venice property shortlist today.
- Ground-floor flood history for the exact address, not the sestiere.
- Acqua alta protection actually installed, and who maintains it.
- Foundation and salt-exposure survey, on top of the usual conformità check.
What does Venice underwriting rest on?
Venice underwriting rests on maintenance far more than it rests on yield, which is the reversal foreign buyers most often miss. The lagoon shortens every maintenance cycle through salt and humidity, works and materials arrive by boat at a premium, and ground-floor space carries acqua alta exposure before a single tax band enters the model.
Venice screening (Q2 2026): San Marco and San Polo €4,200-5,600/m²; Cannaregio and Castello €3,875-4,850/m²; Mestre Centro €1,825-2,675/m²; Marghera €1,150-1,310/m². Historic center STR enquiry remains strong on verified premium-track inventory, but basic 120-day caps compress pro forma revenue for new operators. Long-term Mestre leases deliver 4.0-5.5% gross on tickets €180,000-320,000. Foreign buyer mix: US and UK lifestyle (38%), EU second-home (34%), Australian trophy (10%). Acqua alta insurance and conformità audits are mandatory on pre-1960 lagoon stock below the third floor.
Insider tip: Premium-track municipal registry entries are tied to the owner and unit, not automatically transferable on sale. Verify whether a listing’s STR license chain survives rogito before paying a tourist-income premium.
- Maintenance cycles run shorter here than anywhere else in Italy at comparable prices.
- Budget an all-in 10% to 15% on a non-resident second home before lagoon-specific costs.
What field data can be cited for 2026?
The figures worth quoting on Venice in 2026 are these: San Marco at €4,200-5,600 per sqm, Mestre Centro at €1,825-2,675, and gross long-term yields of 4.0-5.5% on mainland tickets under €320,000. The spread between the two (roughly two and a half to one on price, and the reverse on yield) is the single most useful fact about this market, and it holds across the lagoon and mainland divide.
| Q2 2026 metric | Value |
|---|---|
| San Marco band | €4,200 to €5,600 per sqm |
| Mestre Centro band | €1,825 to €2,675 per sqm |
| Marghera value band | €1,150 to €1,310 per sqm |
| Mestre gross LTR yield | 4.0% to 5.5% |
- Verify premium STR registry chain survives rogito before paying tourist-income premiums.
- Quote polizza alluvione on ground-floor lagoon units before compromesso.
- Budget Soprintendenza timelines at 4 to 12 months on facade-heavy renovations.
Venice screening (Q2 2026) tracked San Marco and San Polo at €4,200 to €5,600 per sqm, Cannaregio and Castello at €3,875 to €4,850 per sqm, and Mestre Centro at €1,825 to €2,675 per sqm. Historic center STR enquiry stays strong on verified premium-track inventory, but basic 120-day caps compress pro forma revenue for new operators. Long-term Mestre leases deliver 4.0% to 5.5% gross on tickets €180,000 to €320,000. Foreign buyer mix runs roughly 38% US and UK lifestyle, 34% EU second-home, and 10% Australian trophy capital. Acqua alta insurance and conformità audits are mandatory on pre-1960 lagoon stock below the third floor.
Venice property investment requires acqua alta flood risk modeling on ground-floor units, lagoon environmental permits on exterior work, and condominium spese on palazzo maintenance that can exceed €6,000 annually on shared facade restoration. CIN and municipal STR overlays apply to short stays; centro density limits favor Mestre and Marghera for new operators. Registration tax runs 9% on cadastral value for second-home resale; IMU runs 0.86% to 1.06% on non-primary homes. Commission Mestre corridors for yield-focused foreign buyers and centro only for licensed STR or trophy resale with seven to ten year holds.
Frequently Asked Questions
Venice suits capital-preservation and regulated tourism income more than pure yield. Historic center stock trades at €3,800-5,600/m² with gross yields often under 3.5% net of costs. Mestre mainland offers €1,800-2,700/m² with stronger residential demand. UNESCO heritage rules, lagoon logistics, and Italy's strict STR licensing stack add compliance cost that must be modelled before purchase.
OMI data for 2026 puts San Marco at roughly €3,800-5,600/m², Cannaregio and Castello at €3,875-4,500/m², and Mestre Centro at €1,825-2,675/m². Marghera peripheral stock starts near €1,150-1,310/m². Transaction costs add 8-12% on top of headline prices for second-home buyers.
Venice and its lagoon have been UNESCO World Heritage since 1987. Most historic center buildings fall under Soprintendenza oversight and municipal PRG limits on volume, facades, and use changes. New residential construction in the lagoon is effectively blocked. Renovations require heritage approvals that add 4-12 months and a 25-45% cost premium versus standard refurbishments.
Since October 2024 Venice runs a two-track STR system in the historic center: up to 120 tourist days per year on the basic track with advance day declarations, or year-round rental on the premium track with SCIA filing, municipal registry enrollment, and in-person guest check-in. National CIN and regional CIR remain mandatory. Premium enrollment closed to new entrants after the initial window, with policy review due by end-2026.
Historic center suits trophy ownership and licensed STR on existing premium-track inventory. Mestre suits long-term residential yield, commuter access via rail and road, and lower acqua alta exposure. Mainland buyers still reach Venice in 10-20 minutes but sacrifice lagoon lifestyle branding on resale to foreign trophy hunters.
Yes. EU citizens purchase on Italian national terms. Non-EU buyers including Americans and British nationals can buy when reciprocity rules with their home country are satisfied. Residency is not required for ownership but determines registration tax rates, IMU exemptions, and income tax on rental income.
Historic center gross yields typically run 2.0-3.5% on long-term leases and 3.0-4.5% on compliant short-term rentals before IMU, management, vacancy, and tax. Mestre long-term gross yields can reach 4.0-5.5% on well-located stock. Net yields after cedolare secca at 21-26% and condominium spese are materially lower.
Acqua alta floods ground and lower floors in sestieri during autumn and winter high tides. MOSE barriers reduce extreme events but do not eliminate localized flooding. Standard home policies often exclude flood damage. Buyers should confirm polizza alluvione coverage, ground-floor risk, and MOSE operational status before signing compromesso.
Historic center life depends on vaporetto ACTV passes, traghetto crossings, and occasional water taxis for heavy deliveries. Renovation logistics require barge permits and canal-side loading windows. Condominio spese in canal-front buildings often exceed €300-800/month. Factor transport time and contractor access into renovation timelines and STR turnover costs.
Rome offers deeper corporate tenant demand and Jubilee-linked tourism volume with similar heritage friction. Tuscany delivers higher gross yields in countryside markets but Florence UNESCO STR caps mirror Venice's regulatory pressure. Venice trades the highest overtourism policy risk in Italy for unmatched global brand liquidity on lagoon stock.
Get an Italy property shortlist
Tell us your budget and region (Tuscany, Lake Como, Puglia, Milan, Sardinia). We reply within one business day with options matched to your goals.