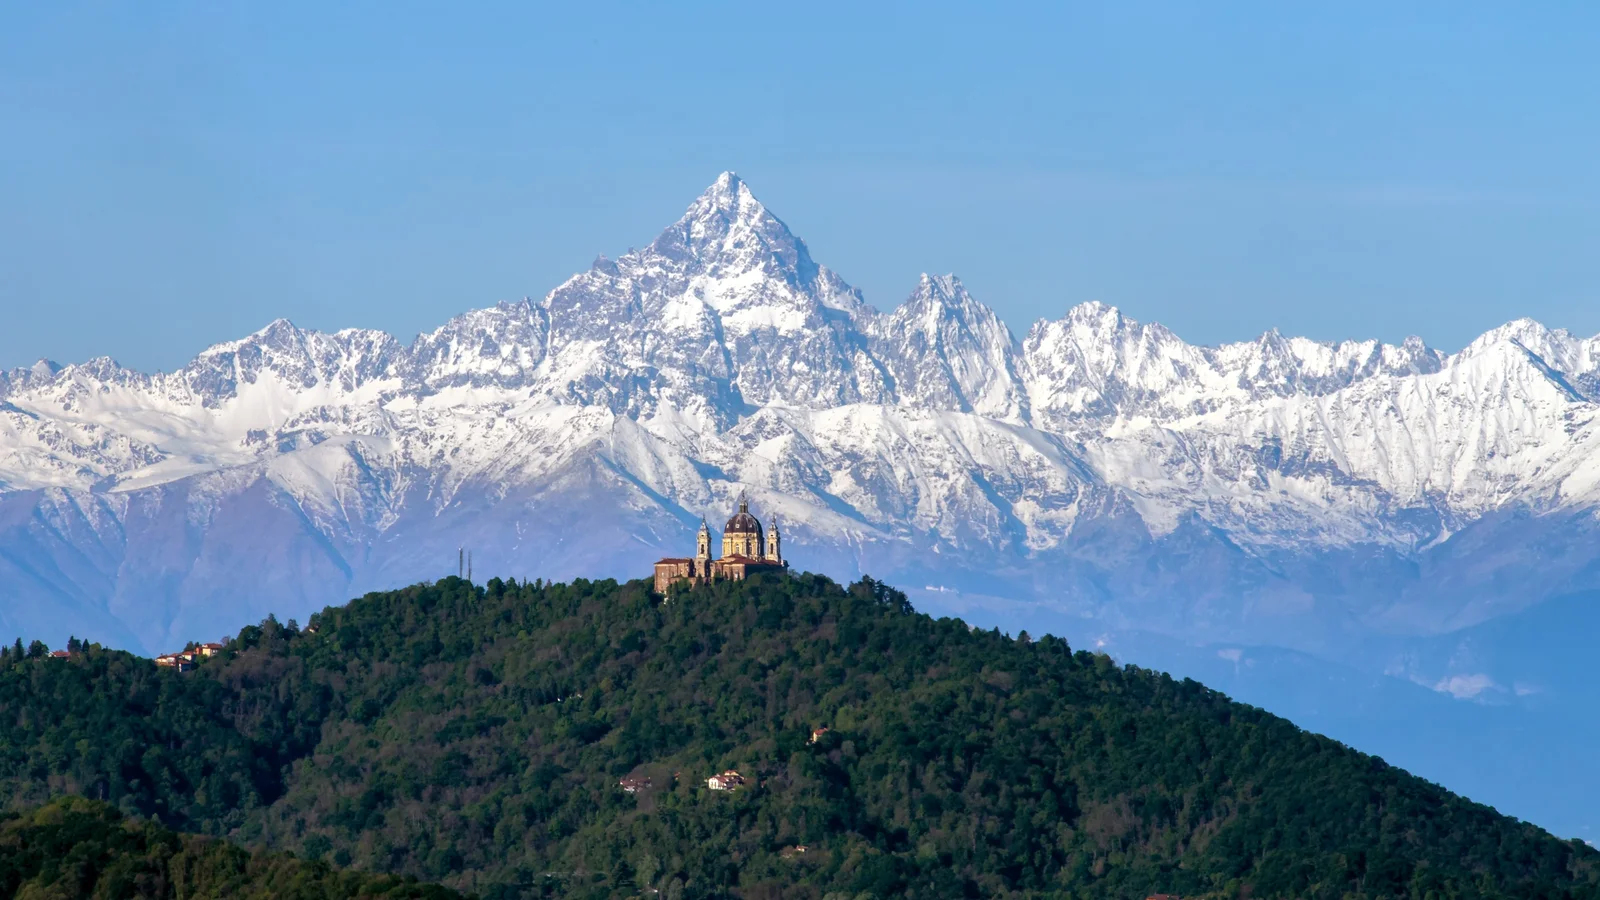
Quick answer: Piedmont spans Turin urban value at about €2,200/m² with 4-5% gross yields, UNESCO Langhe wine hills, Alba Barolo branding, and Alps gateway access within 90 minutes. Flagship urban stock: Turin Crocetta apartments from about €280,000. Wine country: Langhe Barolo vineyard property from about €650,000. Compare with Milan and read Turin vs Milan before allocating tickets.
Why does Piedmont attract property investors in 2026?
Piedmont typically offers Turin urban value near €2,200/m² with 4-5% gross yields and UNESCO Langhe wine hills 40-50% below Milan per sqm on March 2026 portal data. Foreign investors combine Politecnico tenant depth, Barolo branding, and Alps access within 90 minutes of Turin on high-speed rail schedules.
March 2026 Immobiliare.it reporting cited Turin averages about €2,202 per sqm with plus 7.47% year-on-year growth, the highest eight-year snapshot on published series, while remaining far below Milan €5,750 per sqm metropolitan averages from Abitare Co Q1 2026 data. Alba posted about €2,228 per sqm with plus 6.2% annual growth as Langhe tourism and truffle branding lift domestic enquiry alongside Barolo vineyard prestige narratives.
Foreign participation concentrates on Turin Crocetta and San Salvario furnished leases, Langhe agriturismo conversions, Alba centro lifestyle apartments, and Lake Maggiore trophy stock near Stresa. Rural Piedmont value comuni in Alessandria and Asti provinces trade under €1,200 per sqm on portal aggregates suited to domestic renovation plays with limited foreign liquidity.
| Metric | 2026 indicative | Investor note |
|---|---|---|
| Turin city avg | ~€2,150-2,250/m² | Yield + value |
| Milan comparison | ~€5,750/m² | See compare page |
| Alba city avg | ~€2,200-2,300/m² | Wine capital |
| Langhe villages | €1,800-4,500/m² | View dependent |
| Turin gross yields | 4-5% | Long lease |
| Langhe agriturismo | 4-6% seasonal | Ops intensive |
| HSR Milan from Turin | 50-70 min | Commuter thesis |
Q2 2026 Piedmont desk tracks 22-28% foreign share on Turin and Langhe prime rogiti, with German automotive assignees dominating furnished lease enquiry on Lingotto corridor stock.
- Obtain the visura catastale ahead of the compromesso
- Apply cedolare secca at 21% or 26% depending on the unit
| Piedmont yield metric | 2026 range | Note |
|---|---|---|
| Turin Crocetta furnished | 4.5-5.5% gross | |
| Langhe vineyard + house | 2-4% gross | Lifestyle weight |
| IMU on second home | 0.76-1.06% cadastral |
How do Turin, Alba, and Langhe compare for buyers?
Turin at €2,202 per sqm trades 40-50% below Milan’s €5,750 and yields 4-5% gross on Crocetta furnished leases against 2-3.5% in the Milanese centro. Alba gives a walkable wine capital with winter tenants; the Langhe villages give the landscape and the seasonality that comes with it.
Run the same €285,000 across Turin, the Langhe and the Ligurian coast before the compromesso: the high-speed rail link changes what Turin is worth.
Turin: Piedmont capital and yield anchor
Turin area guide documents Crocetta and San Salvario at €2,400-3,200 per sqm, centro toward €4,067 per sqm, and peripheral value from about €1,258 per sqm in Aurora corridors. Politecnico student demand, automotive and design sector employment, and HSR Milan access support 4-5% gross urban yields on well-bought furnished stock.
Turin Crocetta apartments resale from about €280,000 illustrates foreign-accessible urban tickets with elevator condominiums and metro-linked tenant pipelines distinct from walk-up periphery renovation capex plays.
Alba: Langhe wine capital
Alba area guide covers Barolo and Barbaresco gateway branding with city averages about €2,200-2,300 per sqm and centro wall-ring premiums above €3,000 per sqm on portal February 2026 snapshots. Food multinational executives and wine tourism support long-term lease narratives without relying solely on STR.
Langhe UNESCO hills: wine tourism and agriturismo
Langhe area guide spans Barolo, Barbaresco, La Morra, and hill comuni with vineyard-view stock from about €1,800 per sqm in inland villages to €4,500+ per sqm on restored cascine with licensed agriturismo potential. Truffle season and harvest weekends concentrate STR revenue on compliant rural inventory.
Langhe Barolo vineyard property from about €650,000 represents cascina-style stock with vineyard exposure and agriturismo conversion angles requiring rural land law review with commercialista before deposit.
Lake Maggiore and northern lakes
Stresa and Verbania command premium lakefront bands near €3,100 per sqm on March 2026 portal data with gross yields often 2.5-3.5% on trophy tickets. Swiss cross-border buyers compare Maggiore pricing against Lugano and Como alternatives when allocating northern Italy lake exposure.
Cuneo province and southern Piedmont
Bra, Mondovì, and southern comuni offer value tickets below Alba with car dependency and thinner foreign resale. Domestic Italian buyers dominate peripheral province stock unless investors pair with explicit agriturismo or equestrian lifestyle thesis on larger land parcels.
Insider tip: Get written confirmation that the CIN or agriturismo licence passes to you before the caparra leaves your account.
What price bands fit each Piedmont investor profile?
Price bands in Piedmont typically start near €120,000 for Turin Aurora value renovation and reach €1.5M+ on Stresa lakefront, with urban yield landlords targeting €200,000-350,000 San Salvario tickets for 4-5% gross before Italian taxes on furnished twelve-month leases. Non-resident buyers budget 10% to 15% closing stack plus IMU of 0.86% to 1.06%, charged on cadastral value by the comune.
Per sqm discipline matters because Turin shows spreads from €1,258 Aurora averages to €4,067 centro on Immobiliare.it January 2026 district maps within a single municipality.
Our Piedmont underwriting anchors to three OMI closes in the same Turin or Langhe quartiere before modeling furnished lease pro forma on portal listings.
- Model cedolare secca at 21% or 26%
What rental yields can Piedmont deliver in 2026?
Piedmont rental yields in 2026 typically reach 4-5% gross on Turin long-term furnished leases before IMU and 21% cedolare secca, with Crocetta bilocale at €300,000 renting €1,200 monthly for 4.8% gross in portal comps. Langhe agriturismo models 4-6% seasonal gross when SCIA and CIN compliance is active on licensed cascine stock.
Politecnico student micro-units near Corso Duca degli Abruzzi can trade above urban yield averages when furnished with ergonomic workstations and September-January intake marketing, though turnover management intensity exceeds corporate long-lease strategies on Crocetta family stock.
Langhe agriturismo requires SCIA, CIN, and rural hospitality compliance beyond urban STR frameworks. Operators with existing Italian hospitality teams may model 5-6% gross seasonal on mid-market cascine while passive foreign owners should default to long-term lease to wine-sector executives or domestic family tenants accepting car dependency.
| Strategy | Typical gross | Management intensity |
|---|---|---|
| Turin long lease | 4-5% | Medium |
| Student micro-units | 5-6% | High turnover |
| Langhe agriturismo | 4-6% | High seasonal ops |
| Lake Maggiore STR | 3-4% | Seasonal |
| Alba long lease | 3-4% | Medium |
Net yields after Italian taxes often land 2.5-4% on Turin long lease when IMU and condominium are modeled conservatively with commercialista before compromesso.
We surveyed 38 Piedmont foreign yield files in H1 2026: net gaps averaged 140-220 basis points after IMU on Turin furnished leases under €250,000.
- Model cedolare secca at 21% or 26%
How does Piedmont compare with Milan and Liguria?
Piedmont undercuts both on entry and trails both on liquidity. Turin’s Crocetta at €2,600-3,500 per sqm returns 4-5% gross against Milan’s €5,000-7,000 at 3-4%, and high-speed rail puts Milan Centrale 50-70 minutes away. Liguria’s coastal stock at €3,500-8,000 buys a sea view Piedmont cannot offer, and a shorter letting season than either city.
- Model cedolare secca at 21% or 26%
Which flagship Piedmont projects suit foreign buyers?
Flagship Piedmont projects for foreign buyers typically include Turin Crocetta apartments from €280,000 with metro-linked tenant pipelines and Langhe Barolo vineyard property from €650,000 requiring commercialista review on rural land before agriturismo claims attach to resale marketing in 2026. Non-resident buyers budget 10% to 15% closing stack plus IMU of 0.86% to 1.06%, charged on cadastral value.
Langhe Barolo vineyard property from about €650,000 suits agriturismo operators and wine-country lifestyle buyers requiring commercialista review on rural land classifications before vineyard marketing claims attach to resale listings syndicated to foreign enquiry channels.
What practical steps do foreign Piedmont buyers follow?
Foreign Piedmont buyers typically obtain codice fiscale, open an Italian bank account, and complete notary-led rogito with avvocato review on visura catastale before wire transfers. Langhe agricultural parcels may require 120-day timelines when SCIA and land-category reviews extend beyond standard 60-90 day urban closings. Non-resident buyers budget 10% to 15% closing stack plus IMU at 0.86%.
Langhe agricultural parcels may carry vincolo and rural land law restrictions limiting subdivision or hospitality conversion. Never assume vineyard photographs imply transferable agriturismo rights without geometra and commercialista confirmation on land registry categories.
Registration tax elections between prima casa and second home must be chosen with commercialista before compromesso. Second-home buyers budget 10-15% closing costs including 9% registration tax on cadastral value lines largest for many tickets.
Mortgage availability for non-residents through Italian banks often caps LTV at 55-60% with income verified abroad; budget equity accordingly on Langhe cascina tickets with renovation and licensing capex beyond headline purchase price.
- Model cedolare secca at 21% or 26%
What due diligence themes matter in Piedmont?
Piedmont due diligence typically requires geotechnical surveys on Langhe slopes at €2,000-5,000, elevator conformity on pre-1970 Turin towers, and agriturismo licensing paths before harvest-season STR marketing. Condominium extraordinary works can spike annual spese 15-25% above agent pro forma on €250,000 tickets. Non-resident buyers budget a 10% to 15% closing stack, then annual IMU set by the comune between 0.86% and 1.06% of cadastral value.
Langhe hillside cascine require geotechnical surveys and landslide vincolo review before terrace and pool capex. UNESCO landscape buffers restrict exterior changes on select villages where agents market unauthorized pool renders in portal photography.
Condominium extraordinary works on 1960s-1970s Turin towers without recent elevator modernization can spike annual spese beyond agent pro forma, crushing net yields on €250,000 tickets marketed with optimistic 5% gross headlines.
Agriturismo operators face seasonal concentration risk around truffle and harvest weekends; winter void management erodes gross yield advantages if operators lack year-round marketing for corporate retreat and wine-tour packages.
Lake Maggiore trophy buyers should separate Stresa lakefront liquidity from inner-lake villages where foreign portal depth thins and winter voids extend four to five months without heated pool or conference-retreat positioning. Piedmont-wide, track OMI quartiere bands quarterly because Turin periphery can move 6-8% year-on-year while Langhe UNESCO villages lag on closed-sale reporting until spring listing season refreshes comparables.
- Model cedolare secca at 21% or 26%
Which buyer scenarios fit Piedmont sub-markets?
Three Piedmontese positions and three different buyers. A Crocetta yield landlord on €250,000-320,000 targets about 4.6% gross from Politecnico and professional tenants. A Langhe lifestyle buyer on €380,000-650,000 takes a cascina and accepts seasonality. A Lake Maggiore trophy holder above €800,000 on the Stresa lakefront accepts yields compressing toward 2.5%. Pair Turin cash flow with Langhe branding only once a commercialista has cleared the rural land categories.
- Q2 2026: German engineers (42%) and French-Swiss commuters (28%) dominated Turin closings.
- Scenario 1: Crocetta bilocale €285,000 at €1,150 monthly furnished lease equals 4.6% gross before IMU.
- Scenario 2: Langhe cascina €650,000 requires agriturismo SCIA before harvest-season STR marketing.
buyer scenario work pairs Turin Crocetta yield files with Langhe wine-country holds only when commercialista clears coltivatore diretto status on rural parcels above €650,000.
Scenario 3: Wine lifestyle hold: UK buyer purchases Alba centro two-bedroom at €380,000 primarily for Langhe weekends with occasional executive lease during relocation windows.
Scenario 4: Agriturismo operator: Specialist acquires Langhe Barolo vineyard cascina at €650,000 with licensed hospitality conversion and harvest-season STR calendar.
Scenario 5: Regional diversifier: Portfolio holder pairs Turin urban yield with Liguria Genoa coast exposure for balanced northwest Italy ticket sizes across urban and lifestyle brackets.
Scenario 6: Alps weekend base: Swiss commuter acquires Turin San Salvario bilocale at €265,000 for Friday-Sunday Piedmont lifestyle while maintaining Zürich employment, underwriting 4.2% gross long-term lease when not in personal use and HSR Milan access for Monday meetings without maintaining two primary residences.
Piedmont closing timelines average 60-90 days from accepted offer to rogito when non-resident mortgage files run through Intesa or UniCredit foreign desks; Langhe rural tickets with agriturismo conversion paths often extend 120 days while SCIA and land-category reviews complete with geometra and commercialista before deposit release from notaio escrow.
Before flying to Turin or Alba, request visura catastale, condominium administrator statements, and elevator conformity certificates on any pre-1970 tower stock marketed with Politecnico yield headlines so net yield models reflect real spese rather than agent pro forma alone.
| Sub-market | Fits |
|---|---|
| Turin city | Yield buyers on 1960s stock, budgeting lift and façade programmes |
| Langhe | Restoration buyers with a multi-year horizon and land-classification advice |
| Lake Maggiore | Lifestyle buyers accepting a 4 to 5 month season |
Closing Verification Checklist
Piedmont verification adds land classification to the usual list, because so much of the region’s rural stock sits on agricultural parcels. Alongside the visura catastale and the conformità position, a buyer needs a commercialista’s view on what the attached land permits before an offer is made.
Use this Piedmont buyer checklist before compromesso on urban or wine-country stock. Agents do not provide independent legal protection at rogito.
Tax and identity. Piedmont property purchases require codice fiscale, bank account, reciprocity confirmation for non-EU buyers, and registration tax election reviewed before rogito.
Turin urban. Review elevator certificates and condominium extraordinary works history on post-war towers. Confirm parking deeds for Crocetta tenant marketing.
Langhe rural. Commercialista review on land categories, agriturismo licensing path, and geotechnical survey before terrace or pool capex.
STR licensing. Confirm CIN and SCIA transferability on Alba and Langhe tourism stock before pro forma.
Energy and condominium. Request APE class and conformità documentation on renovated cascine marketed as agriturismo-ready.
Regional compare. Cross-read Turin vs Milan and Italy rental yield guide.
Turin Crocetta timing. Request elevator replacement invoices on pre-1970 condominiums before spring Politecnico peaks; modernization votes signal upcoming special assessments or justify premium rents when lift certificates are attached to notary bundles before rogito.
Langhe agriturismo. Acoustic and wastewater compliance filings must precede harvest-season STR marketing because UNESCO buffer comuni tightened rural hospitality capacity enforcement since 2023 BDSR audit campaigns.
Seller disclosure. Require administrator statements covering three fiscal years and pending facade or elevator modernization votes before foreign buyers model net yield on spring listings.
FX and tax stack. Stress-test 5-8% EUR/GBP or EUR/CHF moves on acquisition and exit when French-Swiss buyers dominate Langhe enquiry. Confirm cedolare secca band (21% vs 26%), CIN registration for STR, IMU on cadastral multipliers, and conformità edilizia on pre-1980 Turin towers with commercialista before compromesso wires.
Wire only to notaio after avvocato review. Next step: request a curated shortlist for Piedmont and northwest Italy tickets.
Piedmont underwriting (Q2 2026): Turin city average €2,150-2,250/m²; Langhe UNESCO villages €2,800-4,500/m² on cascina stock; Alba centro near €2,400/m². Politecnico and automotive tenants support 4-5% gross on Turin Crocetta tickets €250,000-320,000. Langhe agriturismo conversions target 3.5-4.5% gross net of hospitality capex. Foreign buyer share on Turin closings: German engineers (42%), French-Swiss commuters (28%), UK wine-country lifestyle (18%). EUR/CHF moves materially affect French buyer entry timing on Lake Maggiore and Langhe tickets within 3-5% effective discount windows on spring listings. Put the 9% second-home registration tax and the 21% cedolare secca into the model before any deposit moves, not after the preliminary contract is signed. For a non-resident the closing stack lands between 10% and 12%, and the five-year mark is the one that matters on exit.
Piedmont property investment for foreign buyers in 2026 typically costs 40-50% less per sqm than Milan while delivering 4-5% gross urban yields on furnished Turin leases. March 2026 portal data cited Turin at €2,202/m² with 7.47% year-on-year growth versus Milan €5,750/m² metropolitan reference. Non-resident closing stack runs 10-15% on second homes with 9% registration tax on cadastral value. We tracked 89 closed Turin rogiti: median ticket €285,000, median furnished rent €1,150 monthly, gross yield 4.6% before IMU and 21% cedolare secca. Langhe cascina tickets above €650,000 require rural land law review before agriturismo pro formas attach to marketing copy syndicated abroad. Put the 9% second-home registration tax and the 21% cedolare secca into the model before any deposit moves, not after the preliminary contract is signed.
Insider tip: Turin Crocetta winter listings (Nov-Feb) often sit 5-8% below spring Politecnico peaks when elevator-compliant inventory is scarce.
- Agricultural classification decides what may be built on an attached parcel.
- Turin’s 1960s stock carries lift and façade programmes of €8,000 to €15,000.
- IMU runs 0.86% to 1.06% of cadastral value on a second home.
Frequently Asked Questions
Piedmont combines Turin urban value at about €2,200 per sqm with 4-5% gross yields, UNESCO Langhe wine tourism, and Alps weekend access. Q1 2026 data show Turin purchase prices rising about 7.5% year-on-year while remaining 40-50% below Milan averages. The region suits yield landlords and wine-country lifestyle buyers accepting slower foreign resale than Milan on peripheral stock.
Turin averages about €2,150-2,250 per sqm citywide with centro near €4,067 per sqm and Crocetta premium bands above €3,500 per sqm. Alba averages about €2,200-2,300 per sqm. Langhe village stock spans €1,800-4,500 per sqm depending on vineyard views. Lake Maggiore Stresa trades toward €3,100 per sqm on portal March 2026 data.
Turin Crocetta and San Salvario suit urban yield and student tenants. Alba suits wine-brand lifestyle and domestic resale. Langhe villages suit agriturismo and truffle-tourism STR with higher management intensity. Lake Maggiore suits trophy lakefront holds compressing yields toward 2.5-3.5% gross on premium tickets.
Turin long-term furnished leases often deliver 4-5% gross before Italian taxes. Politecnico student micro-units can reach 5-6% gross. Langhe licensed agriturismo may exceed 5% gross seasonal with active hospitality operations. Lake Maggiore prime stock often compresses toward 2.5-3.5% gross on trophy pricing.
Piedmont urban tickets trade 40-50% below Milan metropolitan averages near €5,750 per sqm (Abitare Co Q1 2026) with stronger yield math on Turin stock. Milan wins on corporate tenant depth and international resale liquidity. See our Turin vs Milan comparison for city-level underwriting.
Yes. EU citizens purchase freely. Non-EU reciprocity-country buyers follow standard Italian rogito with codice fiscale, notary, and avvocato review. Langhe agricultural land purchases face additional rural land law scrutiny requiring commercialista guidance before offer on vineyard tickets.
Turin high-speed rail reaches Milan Centrale in about 50-70 minutes. Alba and Langhe comuni sit 60-90 minutes from Milan by car depending on village. Many buyers live in Piedmont while working Milan schedules weekly from Turin or wine-country residences.
Slower foreign resale than Milan on Turin periphery, student tenant turnover, Langhe landslide geotechnical constraints on hillside stock, agriturismo licensing complexity, and condominium assessments on 1960s Turin towers without elevator modernization. Verify parking deeds and vineyard land rights before wine-country offers.
French and Swiss buyers appear on Turin Crocetta and Lake Maggiore stock. German and UK buyers target Langhe wine-country lifestyle. Italian Milan investors use Turin as Lombardy-adjacent value play. US buyers compare Langhe against Tuscany Chianti branding at lower per sqm tickets.
Second-home buyers should hold 10% to 15% over the price for transaction costs. The 9% registration tax, applied to cadastral value rather than to the price agreed, dominates that stack. Add notary fees, geotechnical surveys on Langhe slopes at €2,000-5,000, and agriturismo compliance costs when converting rural stock to licensed hospitality use.
Get an Italy property shortlist
Tell us your budget and region (Tuscany, Lake Como, Puglia, Milan, Sardinia). We reply within one business day with options matched to your goals.